Welcome to the final part of our 3-article series on SAFE conversions and dilution where we examined a company that raised 3 rounds of SAFE financing.
We conclude this series with a side-by-side comparison examining dilution in 2 dimensions: (i) Stakeholder perspective (Founders and investors), and (ii) the number of rounds of SAFE financing.
TLDR: Our key findings are:
- Raising capital via SAFEs dilutes Founders. Dilution is more severe for Founders with post-money conversion.
- Post-money SAFEs are favorable to investors since they maintain their ownership stake at the time of conversion.
If additional post-money SAFEs are issued following your investment, more shares will simply be issued upon conversion such that your ownership stake is maintained.
In our example, a company with 100,000 shares (90,000k held by Founders) raises SAFE financings:
- $2MN at $8MN pre ($10MN post)
- $3MN at $15MN pre ($18MN post)
- $5MN at $25MN pre ($30MN post)
The resulting ownership stake at each stage of financing looks like this:
Pre-Money Conversion:

Post-Money Conversion:

You may find these other readings helpful. Article 1 was based on pre-money conversion and article 2 was based on post-money conversion.
Post-money SAFEs are becoming the norm in early stage fundraising. As such, it’s worth reviewing this list of ‘7 Ways post-money SAFES affect Founders and Angel Investors’ for a more comprehensive understanding.
Introduction
Pre-money SAFEs were introduced by Y Combinator in 2013 and became a standard over convertibles for their simplicity.
This was updated to post-money conversion in 2018 and became broadly adopted in H2 2021. Our article ‘7 Ways post-money SAFES affect Founders and Angel Investors’ explains all these changes.
The most substantive impact of this change has to do with dilution. At the time of an equity qualified financing, SAFEs are converted:
- Pre-money SAFEs: Multiple rounds of post-money SAFES results in dilution for both by Founders and investors.
- Post-money SAFEs: Multiple rounds of post-money SAFES places dilution entirely on Founders.
Imagine a company which was founded with 100,000 shares, 90% of which are held by Founder. It subsequently raises 3 rounds of SAFE financing.
- $2MN at $8MN pre ($10MN post)
- $3MN at $15MN pre ($18MN post)
- $5MN at $25MN pre ($30MN post)
During a qualified equity financing, issued SAFEs will convert into equity and be subsequently diluted by the equity round. Let’s assume conversion happens at the SAFE valuation cap.
Here’s a side-by-side comparison of shares issued, ownership and dilution at each stage of financing, assuming the SAFEs convert at their valuation cap.
Step 1: Company Founded
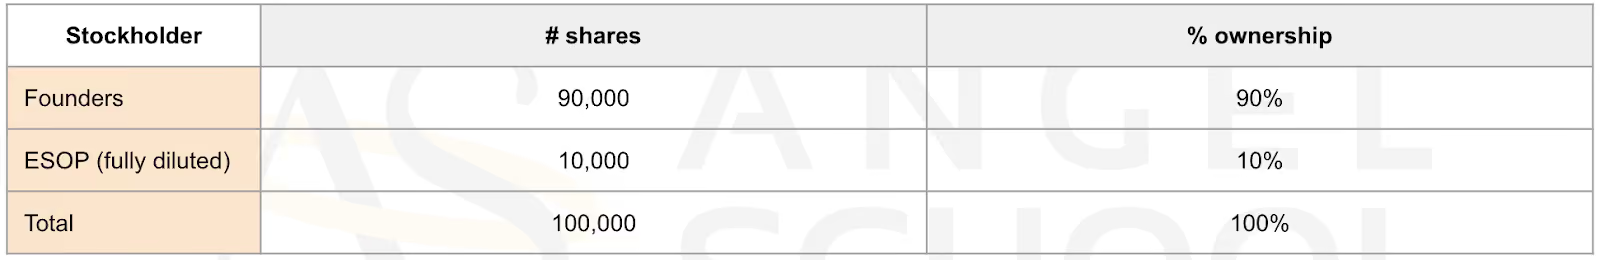
Upon founding the company, 100,000 shares are created and 10% is set aside for current and future employees. The founders retain 90,000 shares and allocate 10,000 to an ESOP.
Their cap table looks like this:
Step 2: Post-Money SAFE 1
The company raises $2MN on post-money SAFE. It has a valuation cap of $8MN pre ($10MN post) and 0% discount.
If an equity financing takes place above the $10MN valuation cap:
The pre-money SAFE converts to equity based on this calculation:
- Share price = $8MN / 100k shares = $80 share price
- Pre-money SAFE 1 receives $2MN / $80 share price = 25,000 shares
The post-money SAFE converts to equity based on this calculation:
- SAFE 1 ownership = $2MN investment / $10MN post-money cap = 20% ownership
- 100,000 shares held by Founders and ESOP constitute 80%
- SAFE 1 therefore will be issued 20% / 80% x 100,000 = 25,000 shares
The resulting cap table comparison looks like this:

Ownership would therefore be identical.

Step 3: post-money SAFE 2
Some time after taking in post-money SAFE 1, the company decides to raise an additional $3MN on a new post-money SAFE. It has a valuation cap of $15MN pre ($18MN post) and 0% discount.
If an equity financing takes place above the $18MN valuation cap:
Pre-money SAFE 2 converts to equity based on this calculation:
- Share price = $15MN / 100k shares = $150 share price
- Pre-money SAFE 2 receives $3MN / $150 share price = 20,000 shares
The post-money SAFEs will convert as follows:
- SAFE 1 ownership = $2MN investment / $10MN post-money cap = 20% ownership
- SAFE 2 ownership = $3MN investment / $18MN post-money cap = 16.6% ownership
- 100,000 shares held by Founders and ESOP therefore constitute 63.3%
New shares will be issued as follows:
- SAFE 1 = 100,000 shares / 63.3% x 20% = 31,579 shares
- SAFE 2 = 100,000 shares / 63.3% x 16.6% = 26,314 shares
The resulting cap table comparison looks like this:

Ownership comparison would look like this.

Notice that with post-money SAFEs, the addition of SAFE 2 does not affect the 20% stake of SAFE 1.
On the other hand, with pre-money SAFEs, the addition of SAFE 2 reduces SAFE 1 ownership from 20% to 17.2%.
With post-money SAFEs, Founders now hold 57% ownership compared to 62.1% if they raised pre-money SAFEs.
Step 4: post-money SAFE 3
Let’s say the company decides to take in additional SAFE financing. They raise an additional $5MN on a new post-money SAFE. It has a valuation cap of $25MN pre ($30MN post) and 0% discount.
If an equity financing takes place above the $30MN valuation cap:
Pre-money SAFE 3 converts to equity based on this calculation:
- Share price = $25MN / 100k shares = $250 share price
- Pre-money SAFE 3 receives $5MN / $250 share price = 20,000 shares
The post-money SAFEs will convert as follows:
- SAFE 1 ownership = $2MN investment / $10MN post-money cap = 20% ownership
- SAFE 2 ownership = $3MN investment / $18MN post-money cap = 16.6% ownership
- SAFE 3 ownership = $5MN investment / $30MN post-money cap = 16.6% ownership
- 100,000 shares held by Founders and ESOP therefore constitute 46.7%
New shares will be issued as follows:
- SAFE 1 = 100,000 shares / 46.7% x 20% = 42,857 shares
- SAFE 2 = 100,000 shares / 46.7% x 16.6% = 35,714 shares
- SAFE 3 = 100,000 shares / 46.7% x 16.6% = 35,714 shares
The resulting cap table comparison looks like this:

Ownership comparison would look like this:

As in step 3, the addition of SAFE 3 does not affect the 20% and 16.6% stakes of SAFE 1 and SAFE 2 using post-money conversion.
On the other hand, with pre-money SAFEs, the addition of SAFE 3 reduces SAFE 1 ownership from 20% → 17.2% → 12.1%.
With post-money SAFEs, Founders now hold 42% ownership compared to 54.5% if they raised pre-money SAFEs.
Conclusion
We conclude that the dilutive effects of post-money SAFEs are more severe for Founders when multiple rounds of SAFE financing are raised. This is because dilution is transferred from investors to Founders. Founders are unlikely to have a free hand in choosing between pre- or post-money SAFEs since this format is being used by Y Combinator.
For investors, this is generally a positive change. Post-money SAFEs reduces early-stage dilution risk. Perhaps more importantly, it imposes fundraising and use of capital discipline on portfolio companies.
The following tables provide a view of dilution if a qualified financing happens following each stage of SAFE financing.
Pre-money dilution:

Post-money dilution:

In case you missed it, here are the other articles in this series: Article 1 was based on pre-money conversion and article 2 was based on post-money conversion.
Post-money SAFEs are becoming the norm in early stage fundraising. As such, it’s worth reviewing this list of ‘7 Ways post-money SAFES affect Founders and Angel Investors’ for a more comprehensive understanding.
About AngelSchool.vc

AngelSchool.vc is the ultimate Accelerator for Angel Investors - from 1st check to leading syndicates as ‘Super Angels’. We give venture investors world-class training, a global community AND build their track record as a member of our Investment Committee (IC).
The AngelSchool.vc Syndicate is backed by 1500+ LPs and deploys $MNs annually. Subscribe here for exclusive dealflow.