Pre-IPO investing is buying a security tied to a private company before it completes a registered IPO.
You are buying shares from an existing investor, most likely through intermediaries, at a valuation negotiated between two strangers separated by an information chasm.
The startup whose stock you're buying is not a party to the transaction, and has no incentive to share information.
TL;DR
- Am I buying shares? In a direct deal with an investor, employee or founder, yes. More often an SPV holding or accessing an allocation.
- What does it cost? Marketplaces take 2 - 4%. Brokers charge 1 - 14%, depending on the deal, demand and check size.
- What due diligence is available? Almost none. If a direct deal yields nothing, an intermediated one yields less.
- Will I make a profit at IPO? The pop goes to the IPO allocation. Half the set trades below its offer price.
- Should syndicates invest in pre-IPO? A deeper discussion, at the end of this article.
What Is Pre-IPO Investing, and 3 Ways to Get In
There are three routes into a private company before it lists, and each one hands you a different legal asset.
One. A primary round. The company issues new stock and the money goes to the company. You are on the cap table with negotiated rights.
Two. A direct secondary. You buy existing stock from an employee, founder or early investor. The cash goes to the seller, and the company must approve the transfer.
Three. An SPV or single-company fund. You buy an interest in a vehicle that holds the stock, or intends to. You are not on the cap table.
| Route | What you own | Who gets your money | The company's role |
|---|---|---|---|
| Primary round | Shares, with negotiated rights | The company | Seller |
| Direct secondary | Shares, subject to consent | The seller | Approves the share transfer |
| SPV or fund | An interest in a vehicle | The sponsor, then the seller | Approves the transaction |
The 1st row is what most investors envision. The 3rd row is the scenario they most commonly encounter.
Almost Everything Here Is Regulation D. Pre-IPO transactions are private placements. Whether you are buying issued shares directly or an interest in an SPV, the exemption doing the work is Regulation D, Rules 501 to 508.
Regulation Crowdfunding and Regulation A exist, and they almost never appear in pre-IPO deals of this kind. They are issuer-led retail offerings with investment caps, and the mature private companies in this article do not use them.
The Argument for Pre-IPO Investments
The surface level arguments are intuitive and attractive at face value.
Investing pre-IPO lowers venture risk and accelerates exits. Secondary deals and employee stock purchases offer a way for angels to enter these positions. You are not underwriting a deck ; you are buying into a company with revenue, a team and a product that already found its market.
The 2nd argument is time. A seed investment takes 7 - 10 years to resolve. A late-stage secondary is pitched at 1 - 3 years.
The underlying assumption is that an IPO is imminent and virtually certain. Labeling it as 'pre-IPO' is technically right, but it is also marketing spin.
The data broadly supports this. Of 22 venture-backed IPOs since January 2024, half now trade at or above their offer price, and the best of them is up more than 850%.
While returns are indeed possible, there are many reasons why pre-IPO investing does not work out, and the rest of this article is about those reasons.
Here's When Secondary Transactions Fall Apart
There are three constraints to every secondary transaction. These are structural and hard to solve.
Information Asymmetry: The Company Is Not a Party.
In all the secondary deals I have seen, I have never received a data room, a pitch deck or company information. The reason is structural. Employees or other investors receive the capital, not the company. The company has no incentive to provide information, and even $1 MN at pre-IPO is trivial to them.
This is the honest reality of a seller in a secondary trade, where even insiders have limited information they can share, likely restricted to investor updates.
In 2024 I discussed Postman shares with a secondary marketplace, 4 times, through 3 different people. My request for basic information was met with this response:
"If you are able to source the information you need from other channels, I am more than happy to help facilitate a secondary transaction."
I replied that a market-maker should bear responsibility for bridging the information gap, or at least making an attempt, since they are charging fees. Here's what came back:
"We would love to solve for that problem, but given the nature of private markets it is a very difficult issue. Occasionally an issuer will open up a dataroom if there is a large institutional buyer interested in their company, but this is rare and typically only occurs where there is some sort of primary investment too."
This is as strong a proof point as can exist. Information asymmetry is a problem that might be solved for large institutional buyers, but not for smaller investors. Marketplaces function as brokers ; they have no direct access to the information either.
Buy-Side Constraint: Limited Market Participation.
Secondary pricing is not set by a crowd. It is set by whoever accepted a bid that week. Sellers need liquidity and buyers never have to show up, which makes this structurally a buyer's market in every period except a mania.
Limited Participation = BIG Price Swings.
The clearest way to see this is at the index level. Forge Global publishes the median secondary trade price against each company's last primary round, and it has published a reading in all but two quarters since 2022. The median opened the 'Funding Winter' 41% below the last round, bottomed at 63% below in September 2023, and did not return to par until June 2026.
| Quarter | Median secondary price vs last primary round | Reading | Forge report |
|---|---|---|---|
| Q3 2022 | −41% | quarter | Oct 2022 |
| Q4 2022 | −50% | quarter | Jan 2023 |
| Q1 2023 | −51% | quarter | Apr 2023 |
| Q2 2023 | −61% | Jun 2023 | Jul 2023 |
| Q3 2023 | −63% | Sep 2023 | Oct 2023 |
| Q4 2023 | −46% | Dec 2023 | Jan 2024 |
| Q1 2024 | −51% | Mar 2024 | Apr 2024 |
| Q2 2024 | −32% | Jun 2024 | Jul 2024 |
| Q3 2024 | −12% | Sep 2024 | Oct 2024 |
| Q4 2024 | −36% | Dec 2024 | Feb 2025 |
| Q1 2025 | −27% | Feb 2025 | Mar 2025 |
| Q2 2025 | −9% | Jun 2025 | Jul 2025 |
| Q3 2025 | −5% | Sep 2025 | Oct 2025 |
| Q4 2025 | −11% | Dec 2025 | Jan 2026 |
| Q1 2026 | −3% | Mar 2026 | Apr 2026 |
| Q2 2026 | par | Jun 2026 | Jul 2026 |
| Q3 2026 | −3% | Aug 2026 | Sep 2026 |
Forge publishes this monthly, not quarterly. Q3 2022 to Q1 2023 are the quarter aggregates it published at the time. From Q2 2023 the quarter-end month is used, except Q1 2025 and Q3 2026, where no quarter-end reading was published and the nearest month inside the quarter is shown.
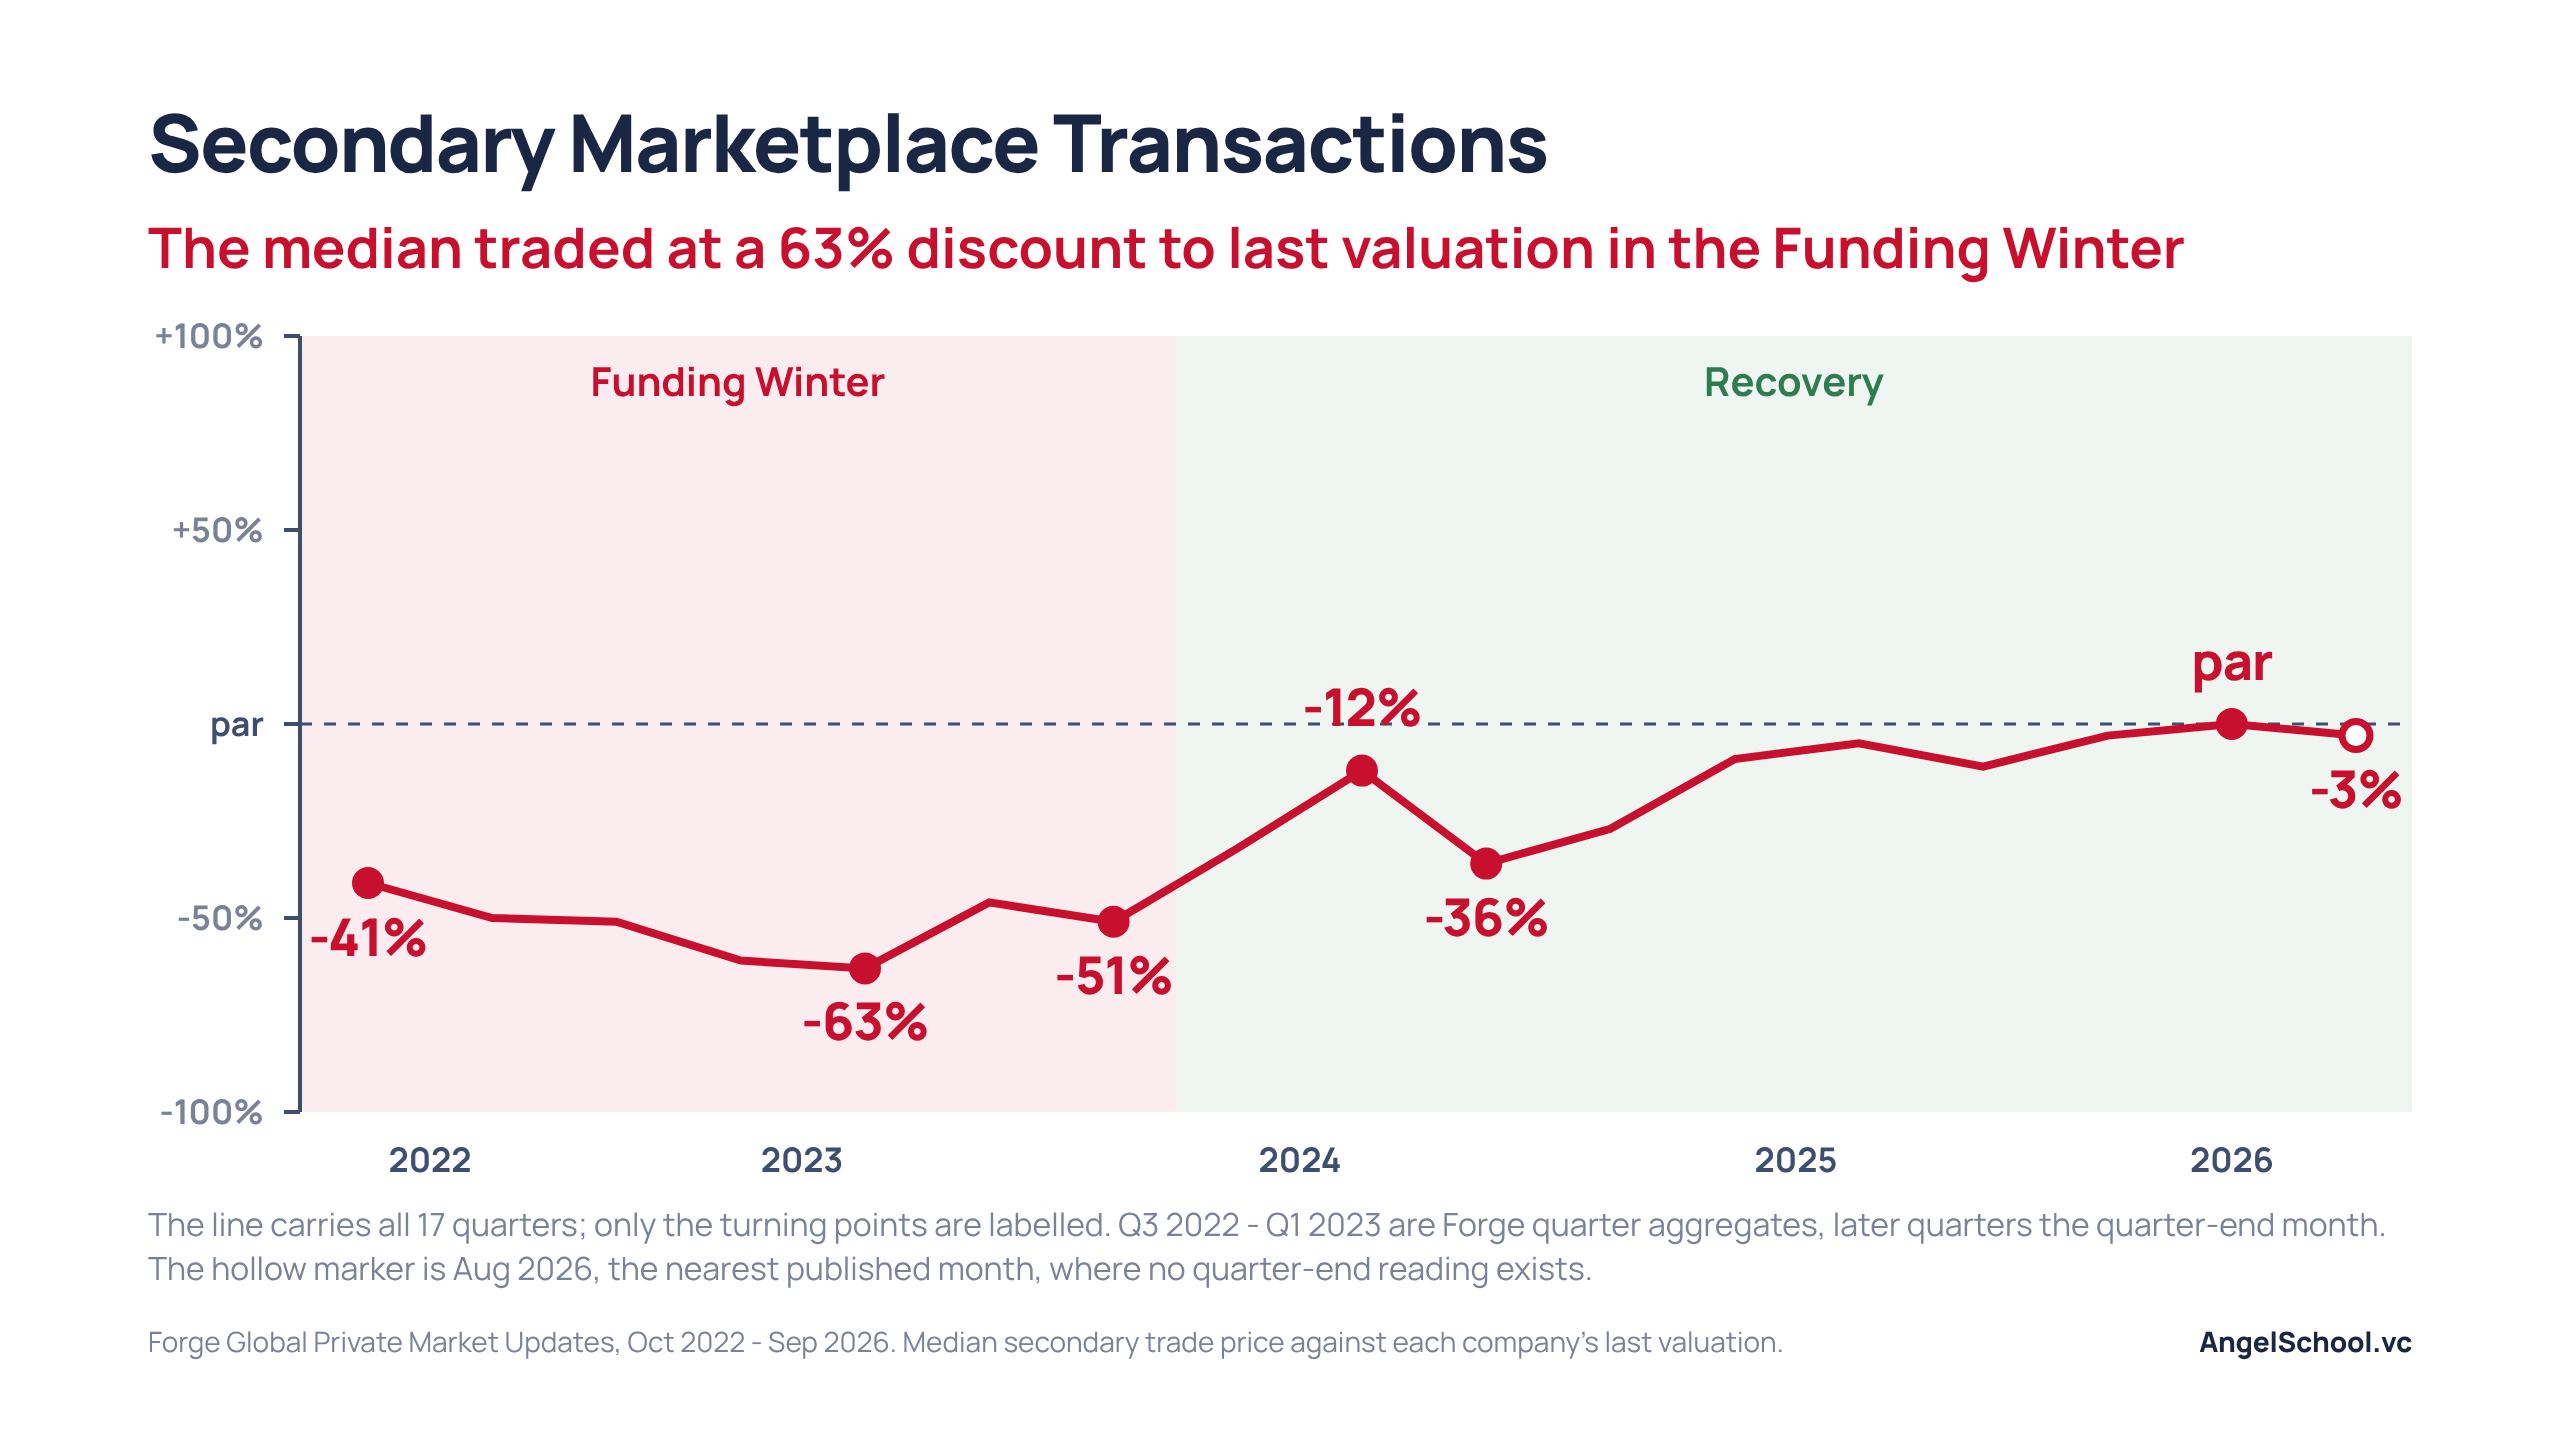
The median fell 22% further over 5 quarters and took another 11 quarters to climb back. No individual company moves fundamentally at that level, much less a whole index at the same time. The driver was capital flight. 2022 was the start of the 'Funding Winter', capital drained from private markets, and that is what caused the secondary price correction.
These are supposed to be the most de-risked assets in venture: late-stage, revenue-generating, close to the exit. If these companies are that good and that close to listing, how does their index valuation fall 63% and recover inside 4 years?
These cannot be true at the same time. It is either an asset problem or, more likely, mispricing driven by something else.
By July 2026 the median had returned to roughly par, but the gap between top and bottom decile deals remained wide.
| Percentile of trades | Price vs last primary round | Source |
|---|---|---|
| Top decile | +27% | Forge, Q3 2026 |
| Top quartile | +7% | Forge, Q3 2026 |
| Median | −7% | Forge, Q3 2026 |
| Bottom quartile | −34% | Forge, Q3 2026 |
| Bottom decile | −57% | Forge, Q3 2026 |
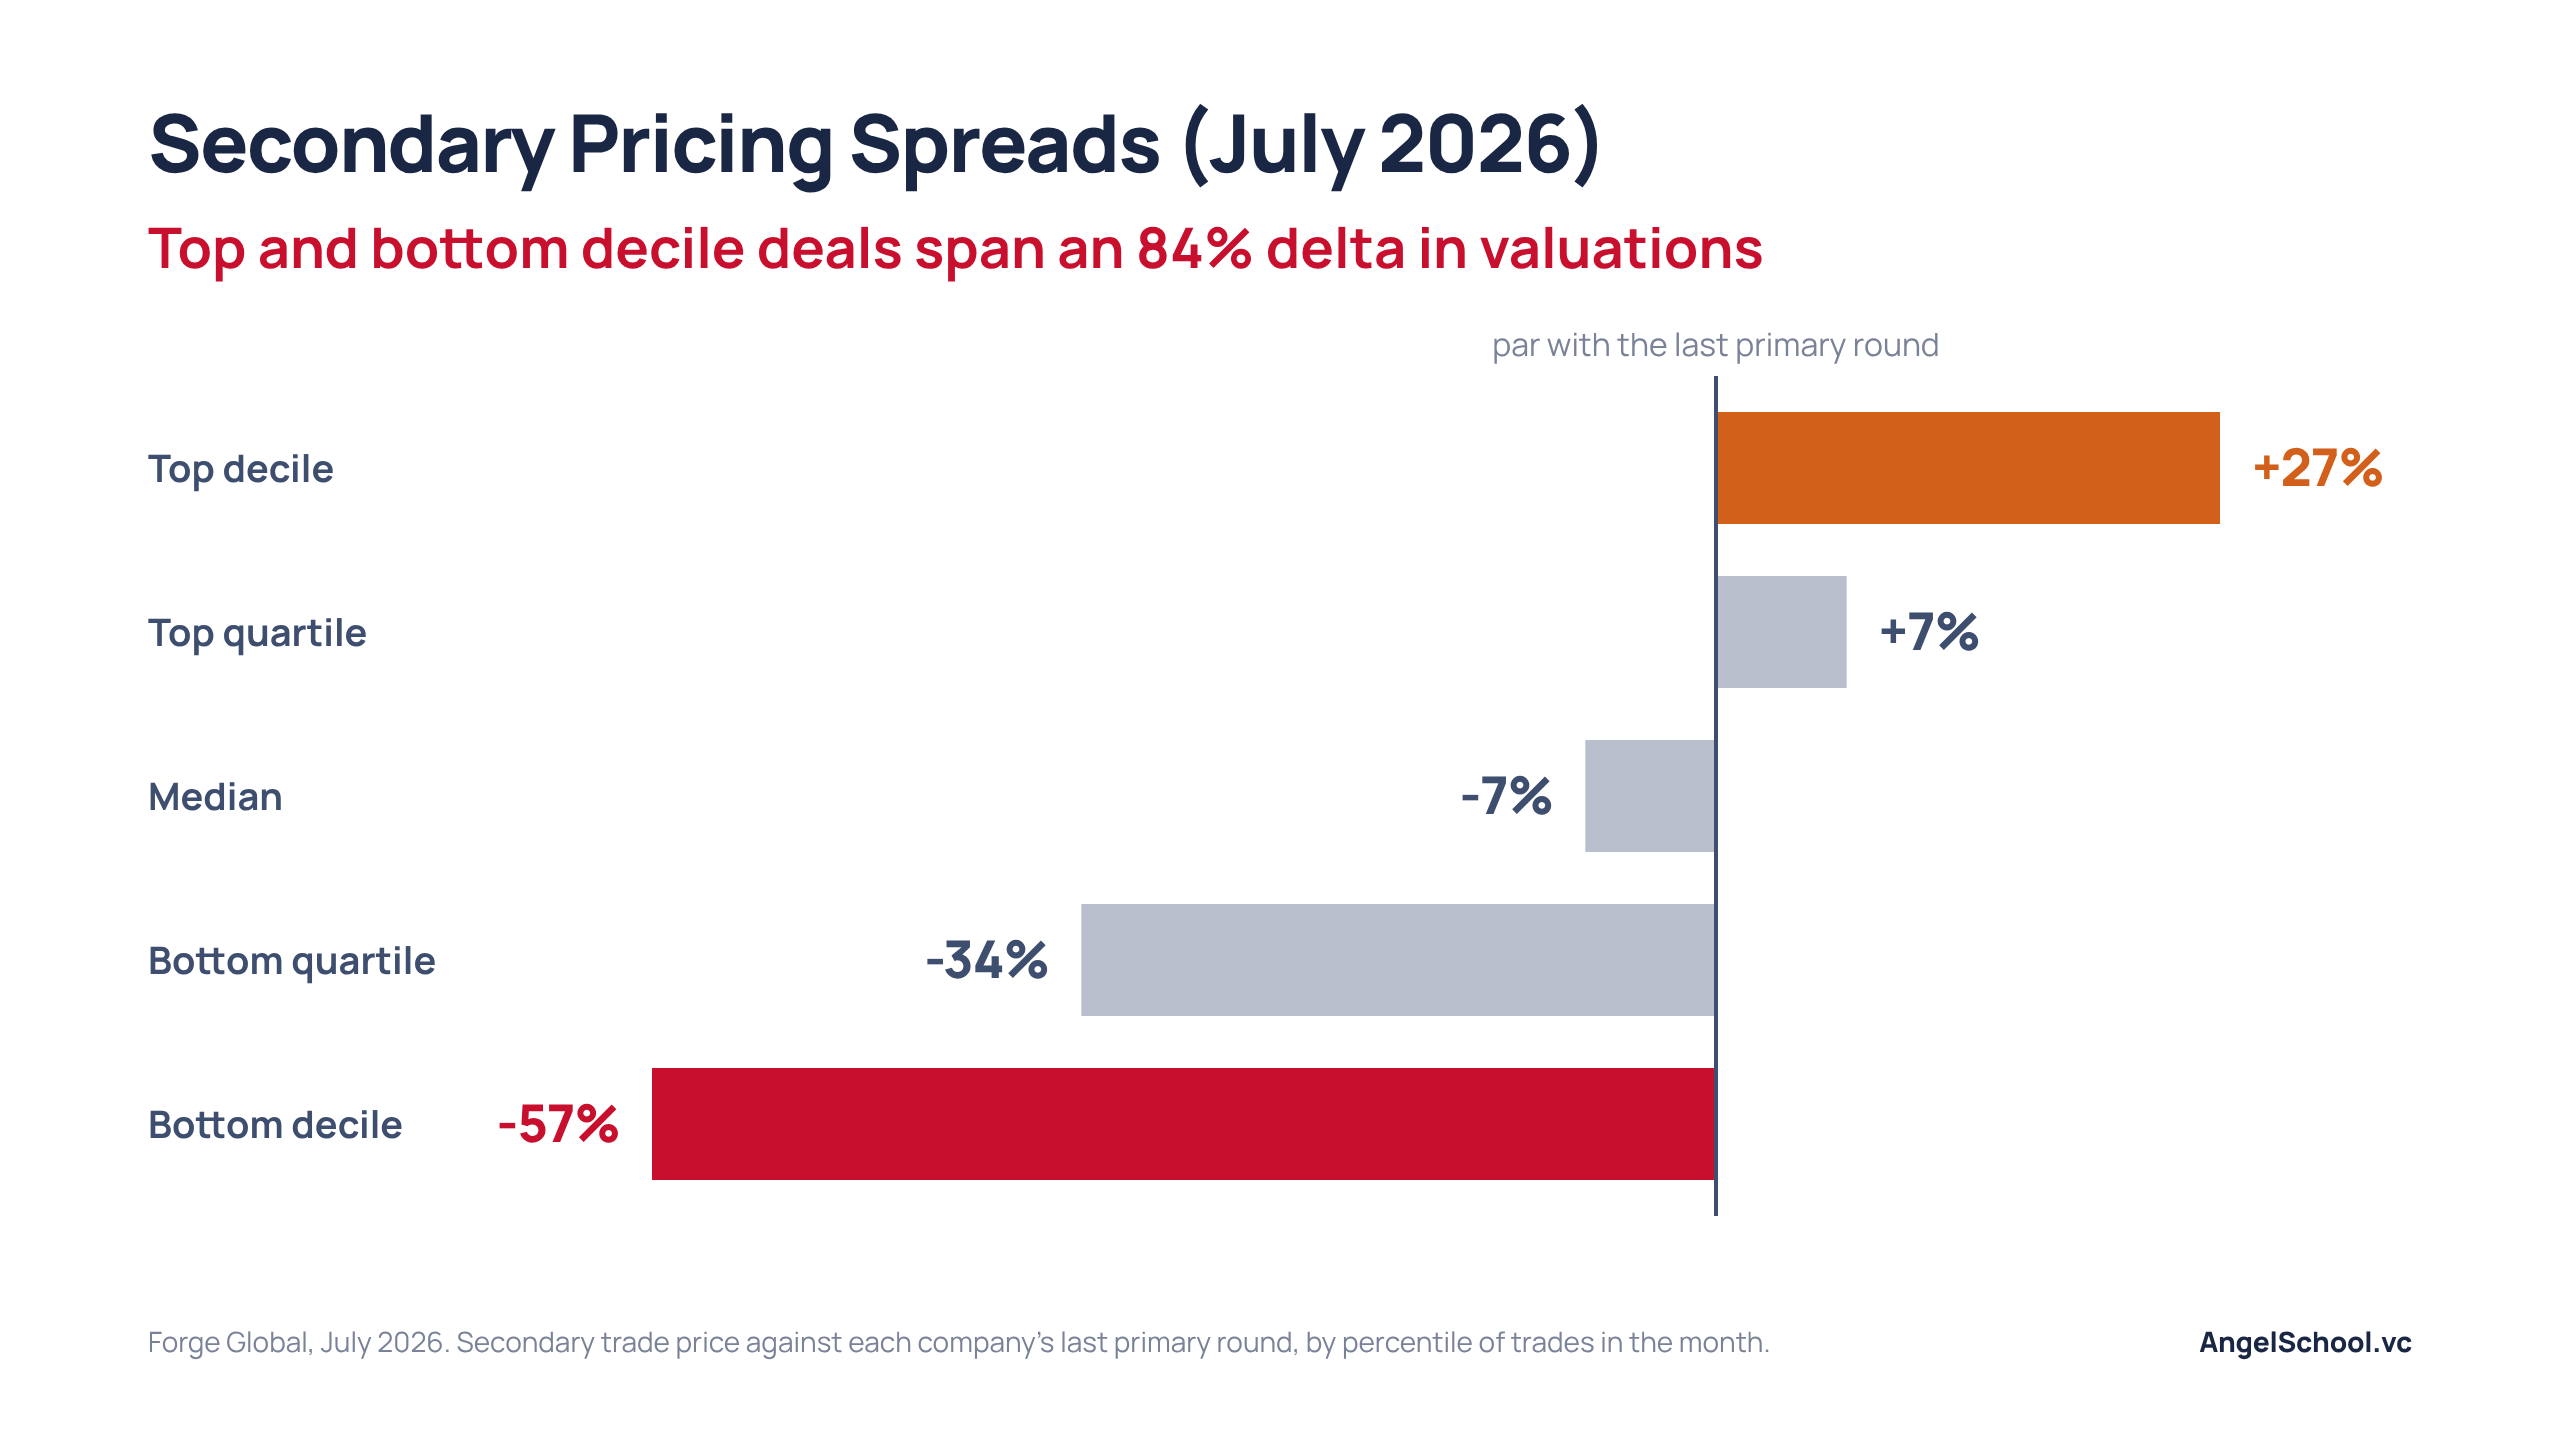
In a single month the top decile traded at a 27% premium to the last round while the bottom decile suffered a 57% discount, a delta of 84%. A handful benefited while it's a bloodbath for everyone else. It's an extremely bifurcated market.
In 2024 the handful was Stripe. In 2026 it is OpenAI, Anthropic and SpaceX, and every other company has a dearth of buyer interest.
Postman Secondaries Price Collapse. Between February 2024 and February 2026 the same marketplace offered me Postman stock 6 times: $14.00, then $12.00, then $10.50, then $11.00, then $10.00, then $7.50, then $8.00. Down 46% from the 1st offer to the lowest, and up twice along the way.
Nothing about a business moves like that. In a market this thin, the price is a transaction record, not a valuation. I have no information on how Postman is performing, and that is precisely the point I am making.
The 1st offer said "Seller of Postman at $14/sh (~80% Discount)".
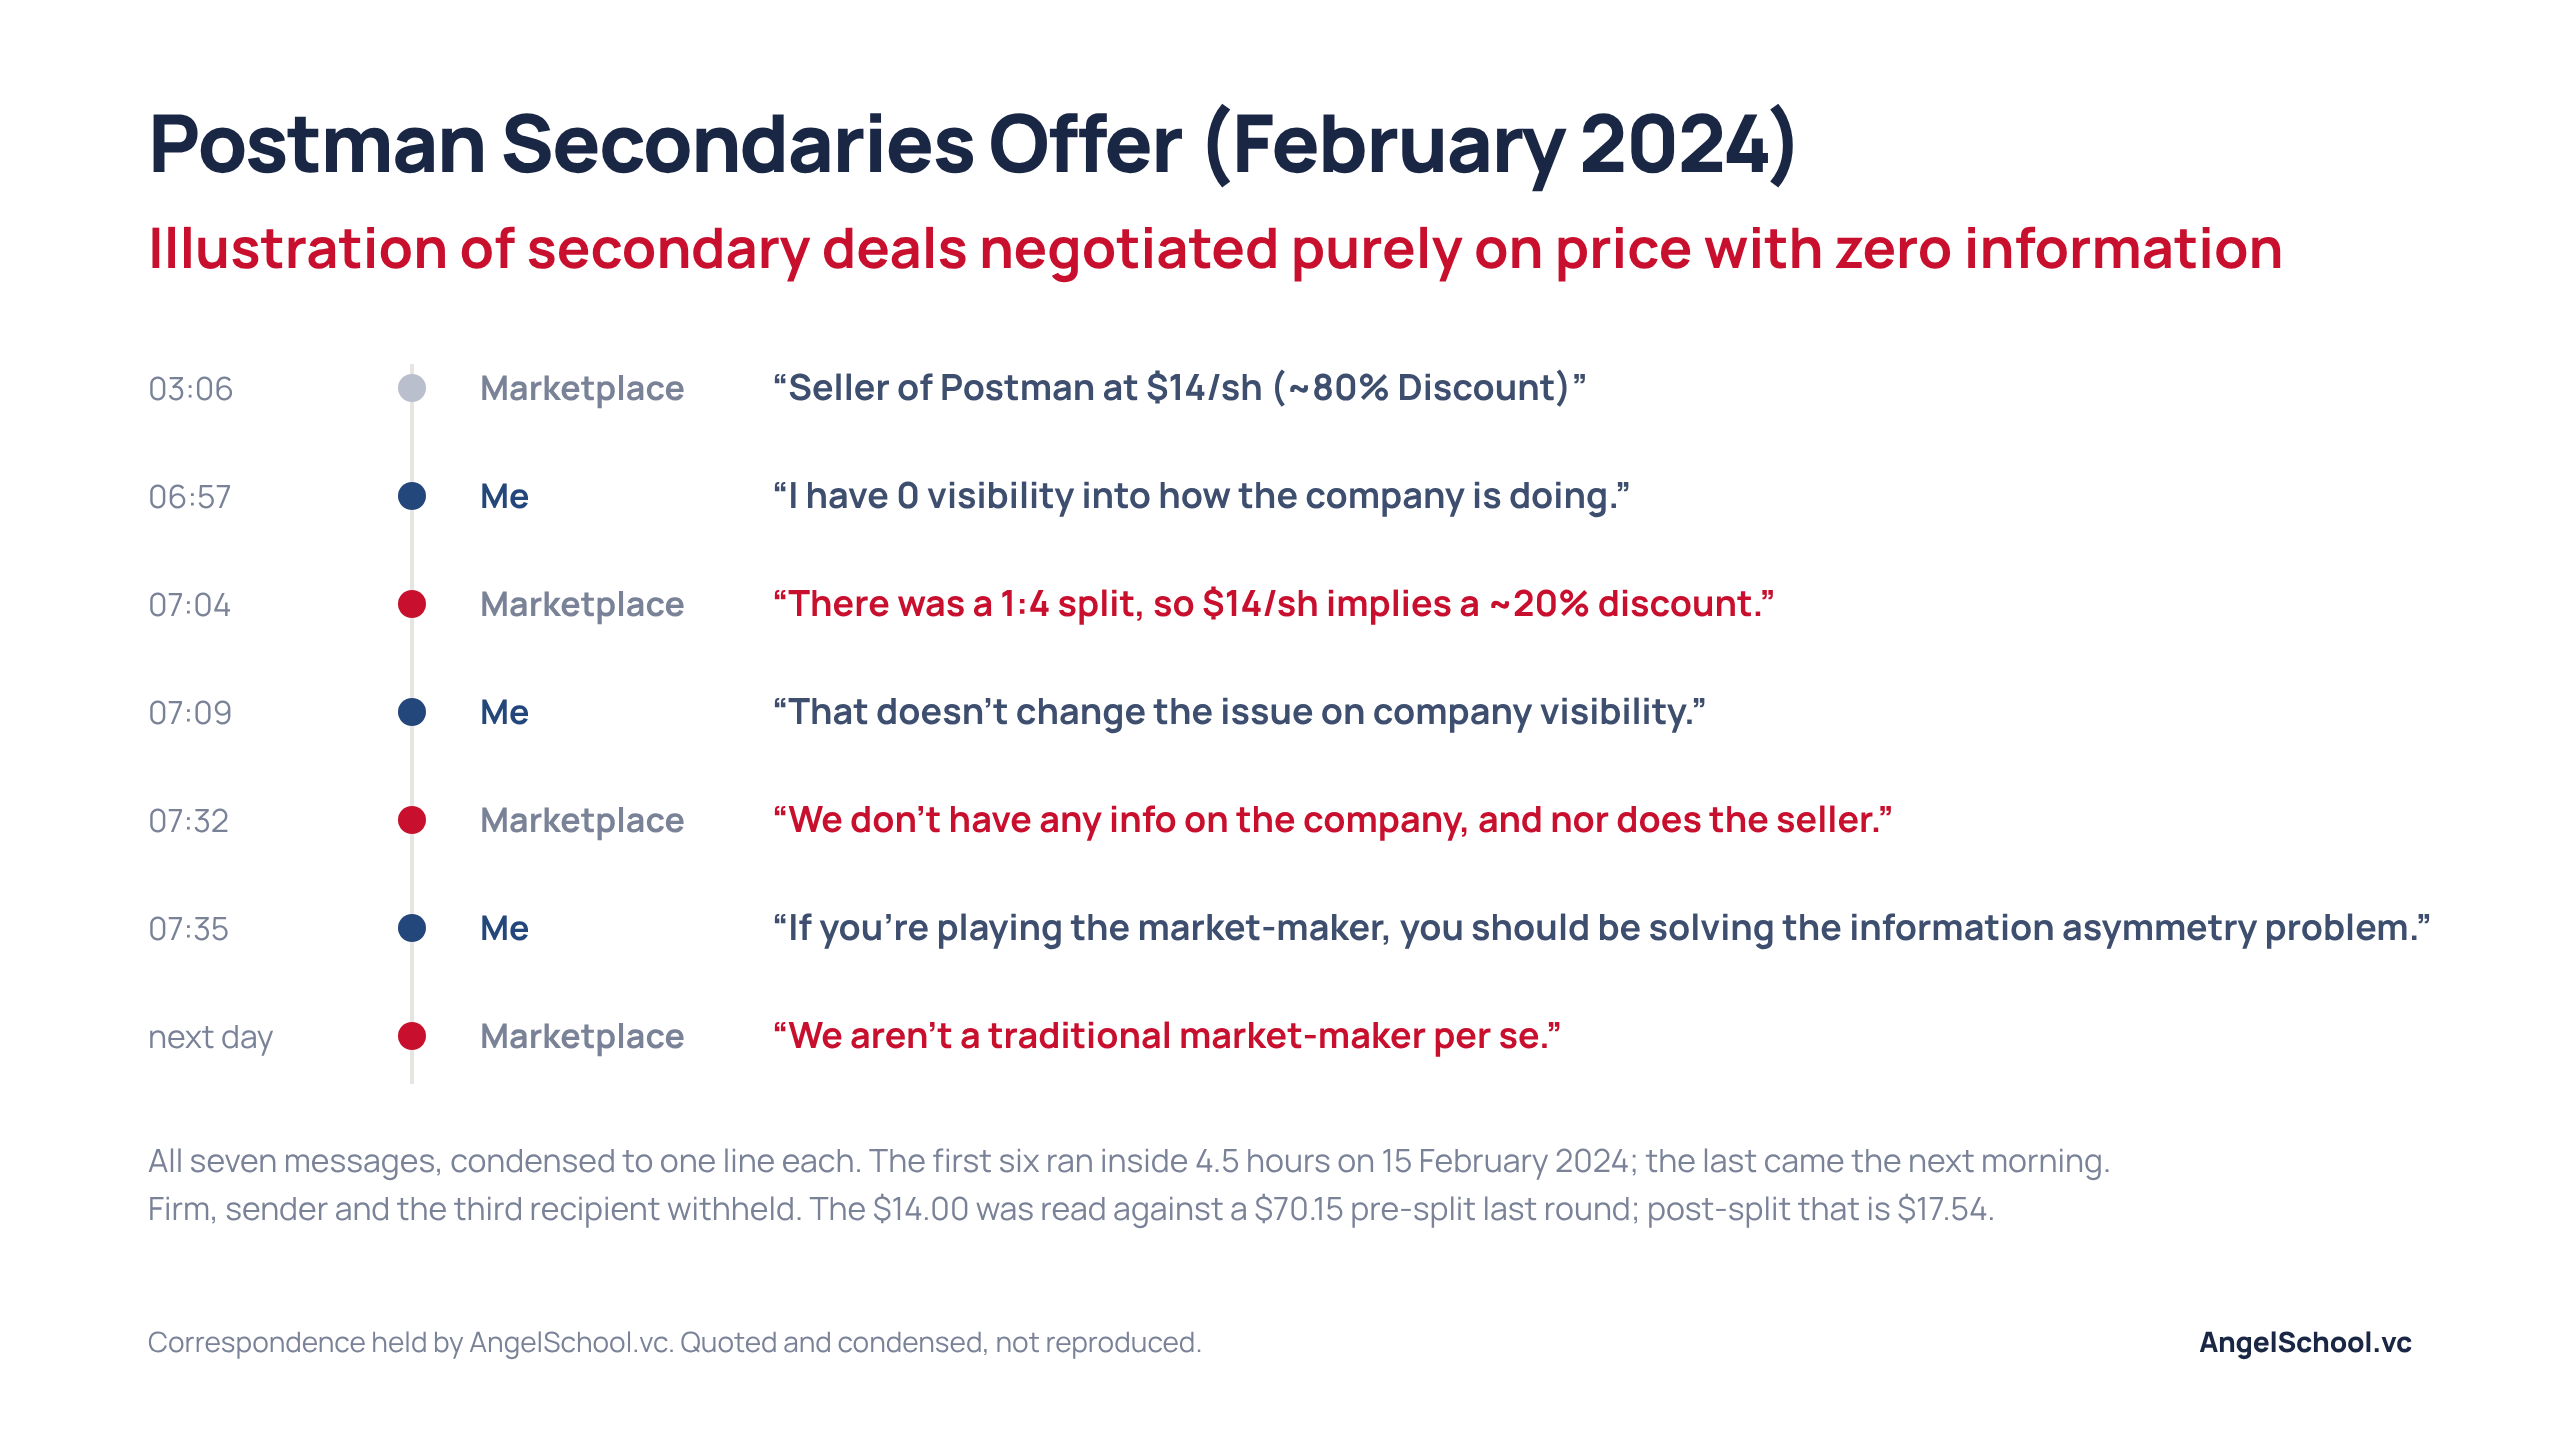
It turned out the firm had used a last-round share price of $70.15 from a third-party database without adjusting for a 1:4 stock split. The post-split figure was $17.54, which made $14.00 a discount of roughly 20%, not 80%. The correction came back the same day after I looked into it.
A headline marketing claim was wrong by 4x and was discovered because I questioned it.
Pre-IPO Investment Costs
SPV Economics vs Secondary Broker Deals. Our recognized standard for syndicate economics is an upfront fee of 5 - 7%, covering the management fee and SPV costs, non-recurring, plus 20% carry. Anything above that is aggressive.
This is a reference point for comparison against brokers.
| Tier | Structure | Upfront cost | Carry | Disclosure |
|---|---|---|---|---|
| Syndicate SPV reference | Single-layer SPV | 5 - 7% | 20% | Full, pre-commitment |
| Secondary marketplaces | Direct secondary | 2 - 4% typical — Forge, Q2 2026 | None | Published fee page |
| Shadow brokers | SPV, often layered | 1 - 14% | Usually none | None beyond your own layer |
| Pre-IPO fund of funds | Fund holding other pre-IPO funds | Fees at both levels | Carry at both levels | Alleged to be concealed |
Secondary marketplaces are the most transparent and cheapest. Brokers, with the benefit of opacity, charge up to 5x more and sometimes even take carry.
The fund of funds is the most expensive structure, because of multi-layer funds and/or SPVs. The fund charges its own fee and carry, and the underlying funds charge theirs. An SEC complaint filed in August 2026 describes exactly this, and we come back to it below.
Secondary Marketplace Fees. Forge was NYSE-listed until Charles Schwab bought it on 2 March 2026 for $636 MN, so its economics sit in SEC filings. Its reported net take rate was 2.8% for FY2024 — Forge Global, FY2024 10-K.
That number understates what a trade costs. The same filing counts both sides of a trade as volume, so a $100 trade is recorded as $200.
On a single trade the real rate is closer to 5.6%.
Shadow Brokers Charge Fees Inverse to Your Check Size. This is the opposite of how the marketplaces work, and it is the part that matters most to an angel.
In December 2025 I was offered a list of 13 late-stage pre-IPO companies, including Anthropic and SpaceX. What stood out was a tiered fee structure: 13% for investments below $100 MN, 7% for $100 - 200 MN checks, and 6% above that.
Direct participation requires institutional scale, and anything smaller requires a layered vehicle.
Enter the Multi-Layer SPV. The same sheet listed one AI company twice, in the same week, on identical "0/0" terms.
Assume $1.00 per share for direct access. Here's how fees and the higher share price penalty compound for the subordinate SPV.
| Direct Allocation | 2nd Layer SPV | |
|---|---|---|
| Minimum check | $100 MN | ~$1.3 MN |
| Share price | $1.00 | $1.15 |
| Fee | 2% | 3% |
| Carry | None | None |
| All-in cost per share | $1.02 | $1.18 |
Investors in the 2nd layer SPV pay 16% more to buy into sought-after secondary shares.
Another company on the same offering sheet had the opposite structure, loading the cost into the fee rather than the share price, with both layers again at 0/0.
| 1st Layer SPV | 2nd Layer SPV | |
|---|---|---|
| Minimum check | $1 MN | $2 MN |
| Share price | $1.00 | $0.99 |
| Fee | 3% | 14% |
| Carry | None | None |
| All-in cost per share | $1.03 | $1.13 |
The 2nd layer confusingly offers a lower price (we're not sure how this is even possible). In aggregate, the 2nd layer SPV investors pay 9.7% more.
At these minimums, a syndicate writing $250k - $1 MN tickets cannot participate in the 2nd layer SPV and would need to add yet another SPV below that! We show the math on this further below.
"0/0" Has No Skin-in-the-Game. Zero management fee and zero carry means the sponsor is not sharing your outcome. The entire economics are the upfront fee, collected at close.
Multi-Layer SPV Economics. Multi-layer SPVs are common, with opaque economics, especially on the subordinate layers.
Secondary Broker SEC Allegations. In an enforcement action filed on 14 August 2026, the SEC alleges that an operator raised more than $74 MN from over 800 retail investors across 11 private funds marketed as pre-IPO access, using more than 100 boiler-room sales agents. Investors were told there were no upfront fees, or at most 12.5%.
The funds are alleged to have bought the shares from entities the operator controlled, at markups averaging approximately 46%, generating roughly $23 MN in undisclosed fees of which more than $12 MN went to sales commissions. More than 90% of the funds' holdings were stakes in other pre-IPO funds.
Market-Makers Don't Own Shares. Shadow brokers and secondary marketplaces effectively operate the same market-making business model. They do not hold inventory, by design.
I have been on the receiving end of cold emails soliciting supply of pre-IPO companies to sell, and being offered the same companies to buy.
FINRA reports that firms failed to confirm whether the pre-IPO funds they recommended had possession of, or even access to, the shares they purported to hold — FINRA, Q1 2026. Nobody paying attention should be surprised. It's not rocket science.
Should Angels Invest in Pre-IPO Secondaries?
It is certainly possible to earn a profit and get liquidity by investing in pre-IPO secondaries. However, doing so comes with risks that many are happy to overlook.
The 'Greater Fool' Theory. Ask why a four- and five-figure check is being offered a company this mature. The allocation has already passed every institution with a relationship, a mandate and better information.
The offering sheet makes it concrete. The direct, low-fee routes carry minimums of $25 MN, $100 MN and $200 MN. You are not being offered the deal the institutions saw, you are being offered the leftovers.
Misaligned Incentives. A 0/0 vehicle pays the marketplace or broker in full once your capital is deployed. Their outcome is settled the day the money moves. Yours is not.
Stripe Case Study. In September 2022 I was offered $10 MN of Stripe founder shares at a valuation of roughly $81 BN, in an SPV. The memo marketed it as a 15% discount to the last round, the $95 BN Series H from March 2021. It projected a gross multiple of 2.56x, and 6.61x on the sponsor's own machine-learning model (I think this is complete bullshit).
10 weeks prior, on 14 July 2022, Stripe cut its internal share valuation by 28%, from about $40 to about $29 per share, as reported by the Wall Street Journal and carried by Reuters. That implies a valuation decline from $95 BN to roughly $74 BN.
So the deal was marketed at a discount while the company had already publicly cut its valuation to below the secondary price offered. The memo does not mention the cut at all.
I declined the deal for obvious reasons. Here is what happened next.
| Date | Event | Valuation | Against the $81 BN entry |
|---|---|---|---|
| Jul 2022 | Internal 409A cut 28% | ~$74 BN | −9% |
| Jan 2023 | 409A reset again | ~$63 BN | −22% |
| Mar 2023 | Series I, $6.5 BN raised | $50 BN | −38% |
| Feb 2024 | Employee tender | $65 BN | −20% |
| Feb 2025 | Employee tender | $91.5 BN | +13% |
| Feb 2026 | Employee tender | $159 BN | +96% |
It took 29 months at that entry price to get back to 1x. As of October 2026 Stripe is still private. The position is 1.96x on paper, with no exit prospects.
Venture-Backed IPO Performance. We tracked 22 US venture-backed IPOs priced between January 2024 and September 2026, sourcing every offer price and lock-up term from the company's own final prospectus.
The question that matters to a pre-IPO holder is not what the company was worth privately. It is what the stock does after the lock-up releases, because that is the first moment they can sell anything.
Not one company in the set closed its first day below its offer price, at a median first-day gain of 24.9%. That pop went to the IPO allocation. A pre-IPO holder was locked up and could not touch it.
By the time they could, half the set had given it back. 11 of the 22 now trade below their offer price, at a median of −4.5% from offer and −12.6% from their day-one close.

When the Peak Private Valuation Was Set Matters More Than the Company. Of the 20 with a sourceable peak private valuation, 10 set that peak before 2022 and 10 set it from 2022 onward. In the earlier group 7 of 10 priced below their peak at IPO, at a median haircut of 54%. In the later group only 2 of 10 did, and 7 of 10 priced above at a median premium of 47%. This is a statement about vintages, not about what any investor paid.
Lock-ups do not release into a friendly market. Only one company's price on its actual expiry date could be sourced: BitGo closed at $5.06 on 20 July 2026 against an $18.00 offer price, down 71.9%.
You cannot escape the gravity of markets, and pre-IPO investing doesn't get around a receding tide.
Should Syndicates Invest in Pre-IPO Companies?
LP demand is real. A brand-name pre-IPO deal is the easiest marketing you will ever do. Going down that route, assuming you can get access to an allocation, will fill that demand quickly and easily.
The problem is that most syndicates do not have direct access to pre-IPO secondaries. You are working through an intermediary, or an intermediary of an intermediary.
At best, a syndicate enters as a 3rd layer SPV in a convoluted chain of fees and carry stacking.
Exhibit A: Economic Erosion From Multi-Layer SPVs. An LP commits $100,000 to a syndicate, which is a 3rd layer SPV. The example assumes fees are set by layers 1 and 2 above it, and shows what the LP in layer 3 eventually pays. Every layer charges 7%, which is the upper end of our own published benchmark and covers the management fee and SPV costs.
| Layer | Capital received | Fee at 7% | Passed to the next layer |
|---|---|---|---|
| 3 · the syndicate the LP joined | $100,000 | $7,000 | $93,000 |
| 2 · the feeder SPV | $93,000 | $6,510 | $86,490 |
| 1 · the vehicle holding the stock | $86,490 | $6,054 | $80,436 |
| Total | $19,564 | 80.4% buys stock |
$19,564 of a $100,000 commitment never reaches the asset. The stock has to appreciate 24.3% before the LP is back to where they started, and that is before anybody charges carry.
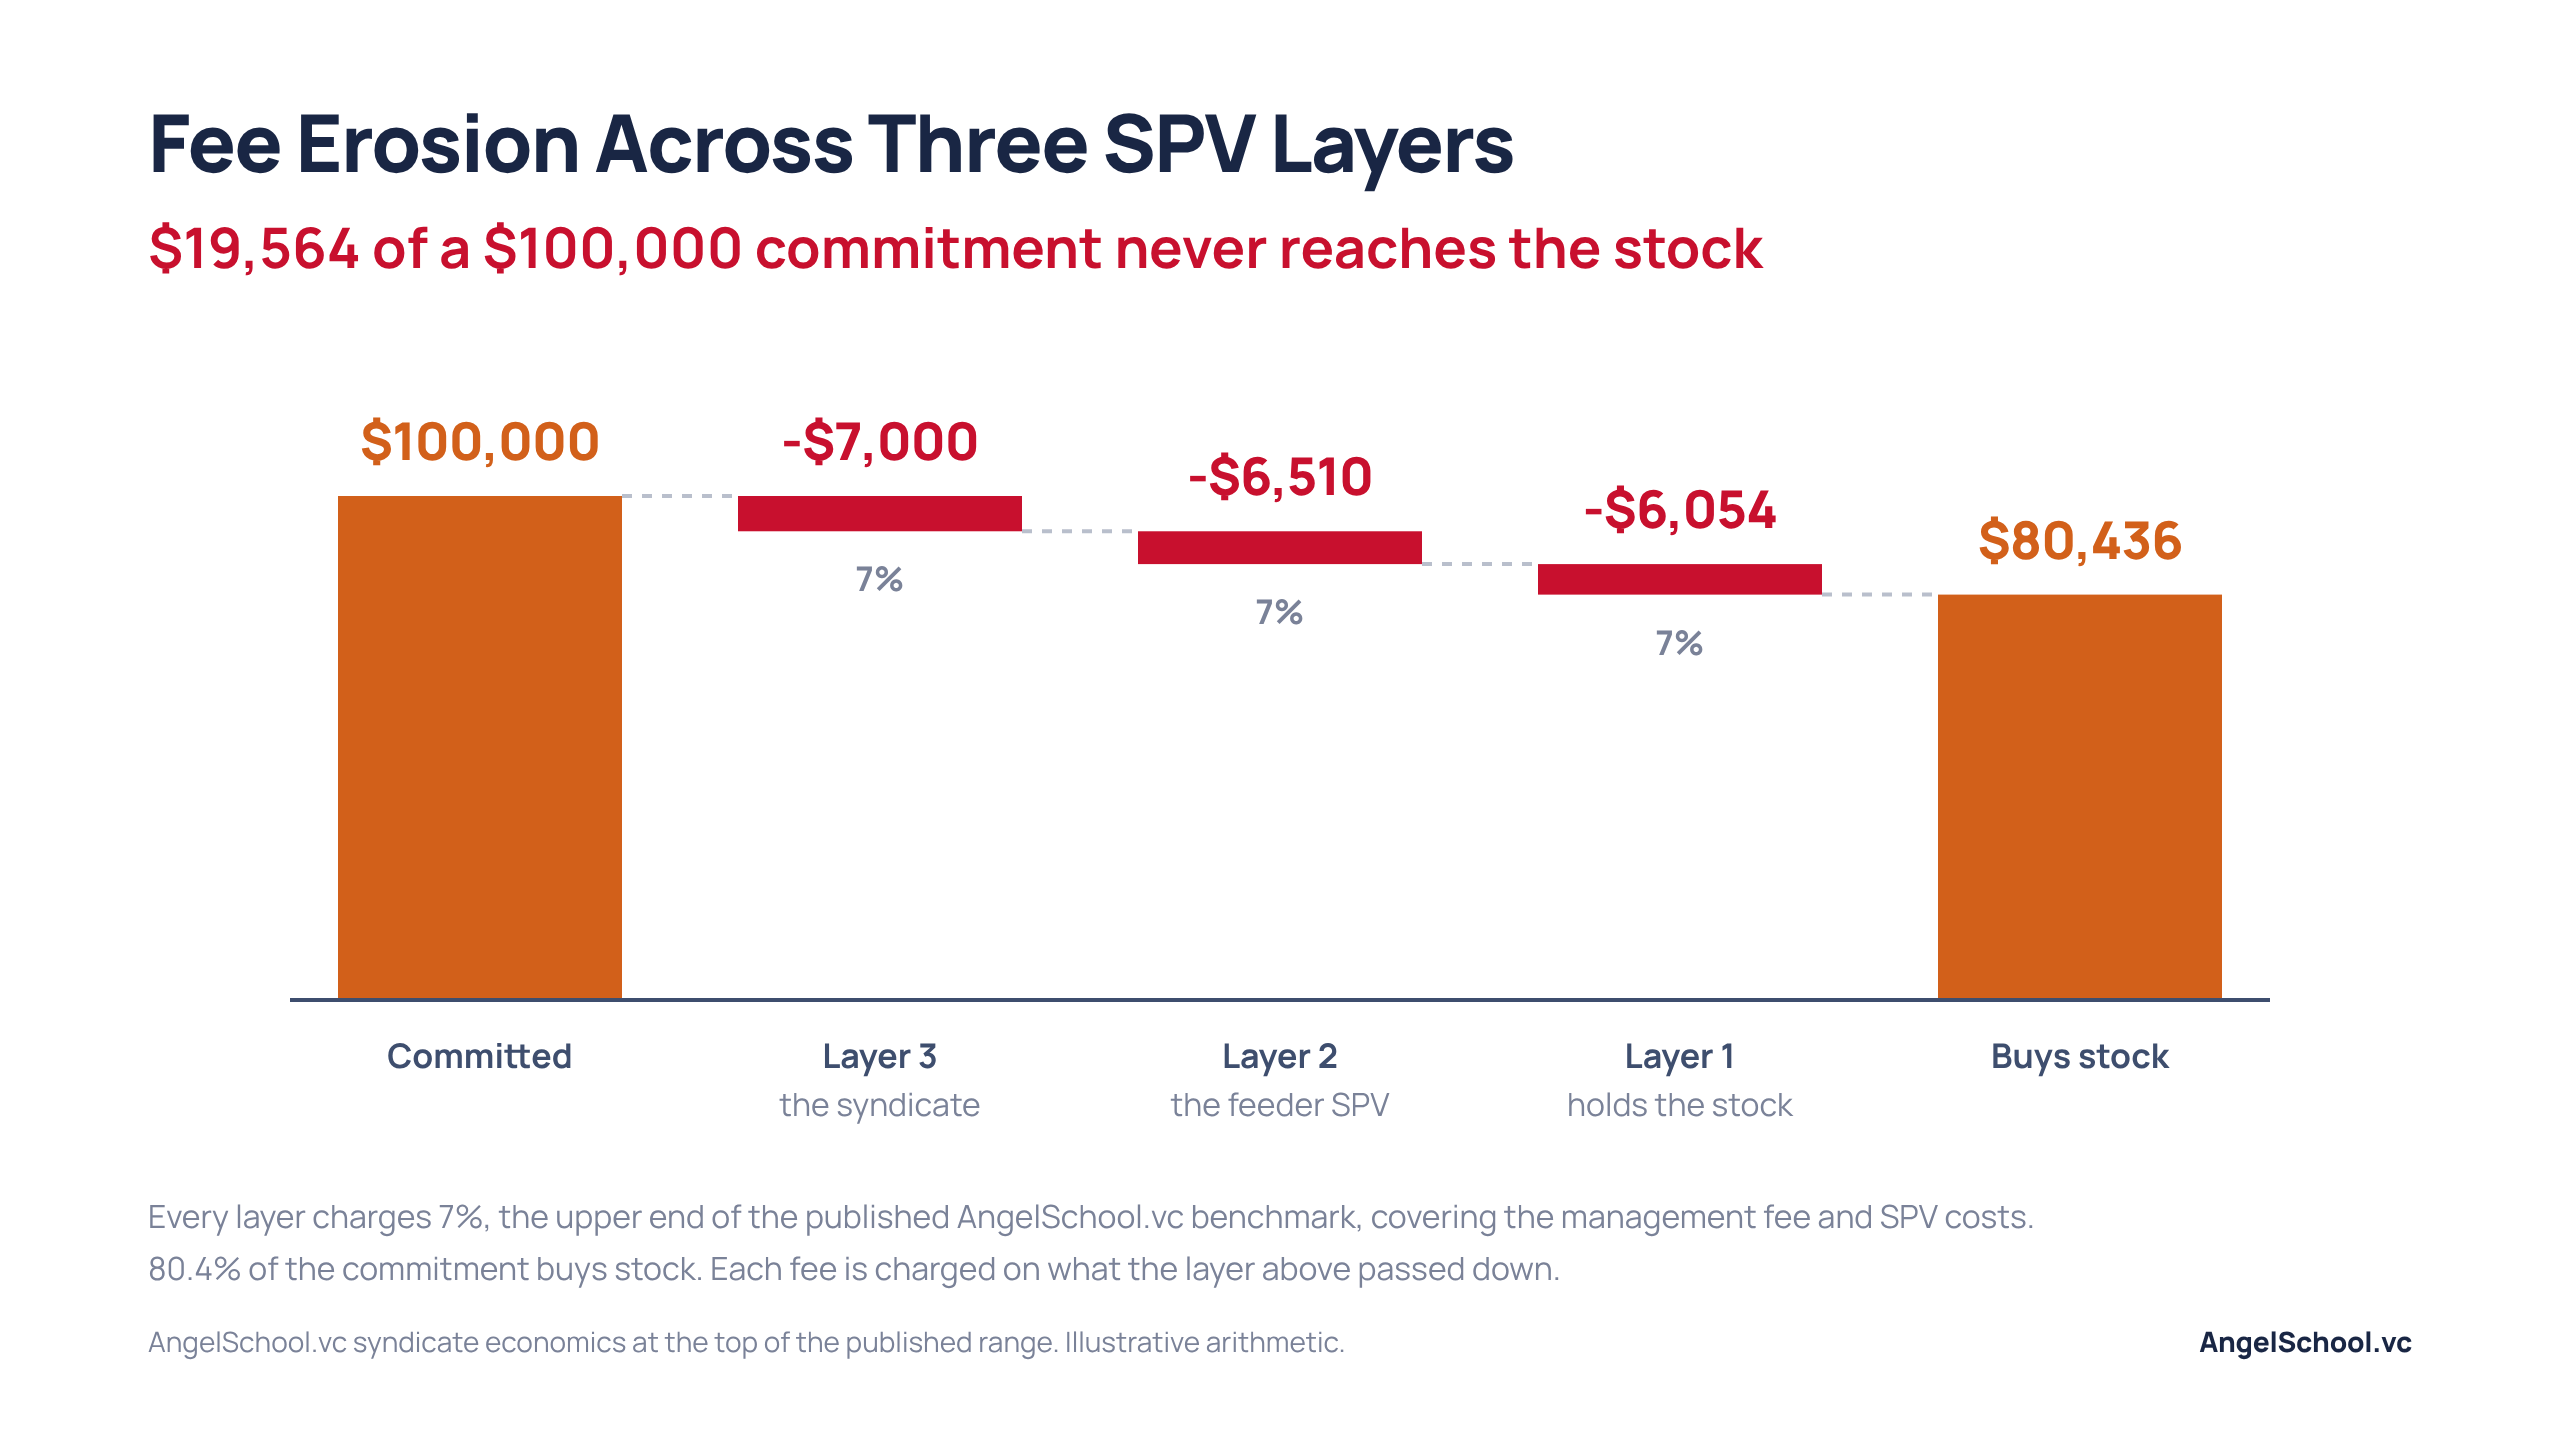
Exhibit B: Carried Interest Load. Fees shrink the capital deployed, leaving a smaller base of what actually gets invested. On top of this, assuming every layer takes 20% carry, here is how LP returns are eroded.
| Gross return on the stock | Gross proceeds | Carry taken across 3 layers | Net to the LP | LP's realised multiple |
|---|---|---|---|---|
| 2.0x | $160,871 | $32,555 | $128,317 | 1.28x |
| 5.0x | $402,178 | $150,312 | $251,866 | 2.52x |
| 10.0x | $804,357 | $346,575 | $457,782 | 4.58x |
A 2x on the stock pays the LP 1.28x. A 5x pays 2.52x. A 10x pays 4.58x. In the 10x scenario you have given up 54% of the gross outcome and paid 35% in carried interest.
Diligence Not Possible. A syndicate aggregating $250k - $1 MN is trivial against a block measured in hundreds of $MNs. That check buys no information rights, no access to management and no data room. The company is not a party to the transaction and has no reason to answer you.
From Syndicate to Broker. You are being provided an allocation, and what you are providing in return is distribution and capitalization. That is brokering.
This begs the question: "Why are you taking carry if you could not undertake diligence?" On a sheet where most structures are 0/0, the market has already priced what selection is worth.
Opaque Economics in Multi-Layer SPVs. LPs frequently pay fees on fees and carry on carry, and it is not disclosed to them.
In the end, what gets these deals done is the brand names of the underlying companies. It has nothing to do with picking fundamentally investable companies that we think will return a multiple.
I am not willing to underwrite my reputation on something I cannot diligence. Many will cross that line, simply because sentiment is there. But that makes you a broker, not an investor.
If You Already Hold Pre-IPO Stock
Your exit options are likely more narrow than they appear. You can get liquidity by exiting into a company's funding round or tender offer, if one is available. You can liquidate on a secondary marketplace, with fees and likely a deep discount to the last valuation. Or you can hold your position and ride it to an exit.
Any transfer of shares between investors must be approved by the company. Rights of first refusal, transfer consents and the restriction language in your investment documents determine what is possible.
6-Month IPO Lock-Ups. Across the 22 prospectuses we read, 9 expire on the earlier of a named earnings release or a day count, which can pull the real release weeks forward.
One company's backstop was 145 days rather than 180. Another layered partial releases at 91 and 120 days for employees selling to cover tax. Two more said "up to 180 days" rather than a fixed term. Read the final prospectus and do not assume the standard.
What to Look at Before Investing in Pre-IPO Deals
Rank the four routes by how much of your committed dollar reaches the underlying company, and you have most of the answer before you look at the deal.
| Rank | Route | What reaches the company | What you own |
|---|---|---|---|
| 1 | Primary round | All of it, less your fee | Shares with rights |
| 2 | Direct secondary | None ; it goes to the seller | Shares, consent permitting |
| 3 | Single-layer SPV | None, less one fee layer | A vehicle interest |
| 4 | Multi-layer SPV | None, less fees you cannot see | An interest in an interest |
Notice that the rankings are inversely correlated with accessibility. The route that puts money into the business is the hardest to reach, and the route most angels are offered has the most intermediaries between the check and the stock.
Here are 6 things you should figure out, in writing, before you commit.
- How many layers sit above you, and what each one charges.
- Which share class you are buying, and what sits ahead of it.
- What the price is relative to the last priced round.
- Every fee in dollars rather than percentages.
- Whether the company has consented, and whether a right of first refusal is live.
- What happens to your money if the transfer is blocked.
Working through that list is mostly structuring, not picking. Our Masterclass: Venture for Angel Investors runs through how early-stage deals are sourced, evaluated and structured, and part two covers venture liquidity and the exit market. Worth doing before the next allocation reaches you.
Upcoming Rule Changes. On 30 September 2026 the SEC proposed amendments on performance-based compensation and interval funds, and separately requested comment on new ways to qualify as an accredited investor, including a FINRA-developed exam and professional credentials such as the CPA, CFA and CFP — SEC, Q3 2026.
The comment periods run 60 days from Federal Register publication. Nothing is adopted, and the credential route today is still Series 7, Series 65 and Series 82.
We believe the fundamental problems around pre-IPO investing are accurate cap table information, updated company performance data, and a source of truth for both. The marketplaces do not solve the information problem. They are market-makers, not a source of truth about the companies they quote.
The question is how to incentivize companies to participate in a market in which they are not a beneficiary. Nobody has answered it yet.
Learn the Rest of It
We built a free masterclass for the venture community on sourcing, evaluating and structuring early-stage deals. Part two covers venture liquidity and the exit market, including secondaries. Check out AngelSchool.vc's Masterclass: Venture for Angel Investors .
This article describes US market practice and general structures as at October 2026. It is not legal, tax or investment advice, and nothing here is a recommendation to buy or sell any security.
Frequently Asked Questions
Is pre-IPO investing legal?
Yes, when the offer and any later resale are registered or fit an exemption, and you meet that route's conditions. The SEC's own investor alert warns that pre-IPO offerings are not registered, and that many offerings marketed to the general public may be illegal because most exemptions do not permit broad solicitation.
Can non-accredited investors buy pre-IPO stock?
Sometimes, through a specific issuer's Regulation Crowdfunding or Regulation A offering. Those carry investment limits, a filing on EDGAR you can read before committing, and resale restrictions that lock you in. What they will not give you is access to the mature private company you had in mind. Those allocations clear through accredited and institutional channels.
What does a right of first refusal mean for my purchase?
It means the company or another entitled holder can take the shares on your terms instead of you, after you have already agreed the trade and priced it. Your capital can be committed and the transaction can still fail through no fault of yours. Establish before you wire whether a right of first refusal is live and what happens to your money if it is exercised.
How do I know if the price I am offered is fair?
In the end the pricing mechanism comes down to supply and demand, and any information you have to inform pricing helps you as the buyer. The Stripe example above shows what happens without it: a deal marketed as a 15% discount to an 18-month-old round sat above the company's own current valuation, which had been public for 10 weeks and was not mentioned.
How long until a pre-IPO company actually lists?
There is no answer to this, and anyone who gives you one is guessing. I was offered Stripe secondary in September 2022 on a thesis of near-term liquidity. It is October 2026 and the company is still private, which is 4 years of an illiquid position against a timeline that was pitched at 1 - 3 years. Price the possibility that the listing never comes.
Do pre-IPO investors make money when the company goes public?
Across 22 venture-backed IPOs since 2024, it depended on when the peak private valuation was set rather than on the company. Where that peak was set before 2022, 7 of 10 priced below it at IPO, by a median of 54%. Where it was set from 2022 onward, only 2 of 10 did.
Is a 2.56x projection in an investment memo worth anything?
It is worth exactly what the assumptions behind it are worth, and those are rarely shown. The Stripe memo above projected 2.56x gross and 6.61x on a proprietary model. Four years on, the position is at 1.96x on paper, before fees, with no exit.
Should my syndicate run a pre-IPO secondary deal?
Only if you can diligence it, which on a check of $250k - $1 MN you almost certainly cannot. If you cannot, you are distributing an allocation rather than selecting an investment, and charging carry on that is charging for work you did not do.
This article describes US market practice and general structures as at October 2026. It is not legal, tax or investment advice, and nothing here is a recommendation to buy or sell any security.
About AngelSchool.vc

AngelSchool.vc is the ultimate Accelerator for Angel Investors - from 1st check to leading syndicates as ‘Super Angels’. We give venture investors world-class training, a global community AND build their track record as a member of our Investment Committee (IC).
The AngelSchool.vc Syndicate is backed by 1500+ LPs and deploys $MNs annually. Subscribe here for exclusive dealflow.