An angel investing platform is simply any website that individual investors use to find and invest in early-stage private companies and startups.
Most comparisons group the options into one list. We see two different markets: crowdfunding platforms on one side, syndicate platforms on the other.
Each has a different business model, different fees and economics, and sits under a different regulatory structure. The distinction matters, because a $100 ticket into a consumer brand and a $25k check into a seed round are very different things.
TL;DR
- Which Platforms Can I Invest Through? Accreditation is the gating factor for access. Reg CF platforms are open to everyone. Reg D platforms require investor accreditation.
- Will Regulations Change? Possibly. The INVEST Act would let anyone qualify as accredited by passing a free SEC exam. It passed the House 302 - 123 on 11 December 2025 and has sat in the Senate Banking Committee since. It is not law.
- What Do Crowdfunding Platforms Charge? 8.1% of proceeds all in, and in 47% of closed offerings the platform also takes stock in the company — SEC, May 2025.
- How Many Reg CF Raises Actually Close? 3,869 of 8,492. The other 4,623 reported raising nothing — SEC, May 2025.
- How Have Crowdfunded Startups Performed? Of 3,253 companies that raised, 8 reached an IPO and 71 were acquired — SEC, May 2025.
- How Do I Decide Where to Invest? On deal quality and the diligence you are given, not on fees. Accreditation then decides what you can access.
Crowdfunding vs Syndicate Platforms
The SEC runs two exemptions that matter here, and which one a platform is built on decides everything downstream.
Regulation Crowdfunding is open to any investor. A company can raise up to $5 MN in a 12-month period, non-accredited investors face annual limits tied to income and net worth, and every offering is filed publicly on Form C. Wefunder, StartEngine, Republic and Netcapital sit here.
Regulation D, specifically Rule 506(b) and 506(c), is closed to anyone who is not accredited. No raise cap, no public financials at the offering stage, higher minimums. AngelList syndicates, OurCrowd and every lead-run SPV sit here.
Accreditation today is a wealth test: income above $200k individually or $300k jointly in each of the two most recent years, or net worth above $1 MN excluding your primary residence.
Both markets reward the same skill: knowing which deals are worth your money. We cover how we do it in AngelSchool.vc's Masterclass: Venture for Angel Investors.
Accreditation Is Becoming More Stringent (and Looser at the Same Time)
The INVEST Act (H.R. 3383) passed the House 302 - 123 on 11 December 2025 and went to the Senate Committee on Banking, Housing, and Urban Affairs on 15 December.
Two of its sections pull in opposite directions.
One. The FINRA Knowledge Test. Section 203 directs the SEC to stand up a free certification exam within a year of enactment, administered by a national securities association. Pass it and you are accredited, whatever your income or net worth.
Two. The Wealth Bar Gets Higher. Section 201 writes the existing thresholds into statute and requires them to be adjusted for inflation every five years. They have not moved since the 1980s. Indexing them raises the bar.
Effectively, money stops being the only way in, and money alone gets more expensive. Two earlier House bills adding license, education and experience pathways sit in the same committee.
None of this is law. The Senate has not acted and no floor vote is scheduled. If you are reading this because you are not accredited yet, Reg CF is what is open to you today, and we cover investing without accreditation separately.
How Crowdfunding (Reg CF) Platforms Operate
A crowdfunding platform is a broker. It brings a company to market and gets paid when the raise closes.
Crowdfunding Business Model. The SEC's Division of Economic and Risk Analysis went through every Form C filed between 16 May 2016 and 31 December 2024. The figures below cover the 3,869 offerings that actually closed and took investors' money.
| What the platform takes | Offerings that raised money |
|---|---|
| Cash commission (% of proceeds) | 6.6% mean, 6.0% median |
| Offerings where the platform also took stock | 47.1% |
| That stock, as % of the offering (where taken) | 2.4% mean, 2.0% median |
| Total all-in compensation | 8.1% |
SEC Division of Economic and Risk Analysis, May 2025. Base: the 3,869 offerings reporting proceeds on Form C-U.
Notice that in 47% of the offerings that raised money, the platform took stock in the company on top of its cash commission. The broker takes equity from the company in addition to its cash commission. This is permitted under Rule 300(b).
Wefunder charges the company a 7.9% success fee on the raise plus $1,000 a year in admin, with no upfront cost. Republic markets a 6% platform fee.
A Reg CF offering must run through one intermediary, and that intermediary is either a registered funding portal or a registered broker-dealer. Both are crowdfunding platforms. Offerings taken through a broker-dealer carried higher fee loads, around 10% — SEC Division of Economic and Risk Analysis, May 2025.
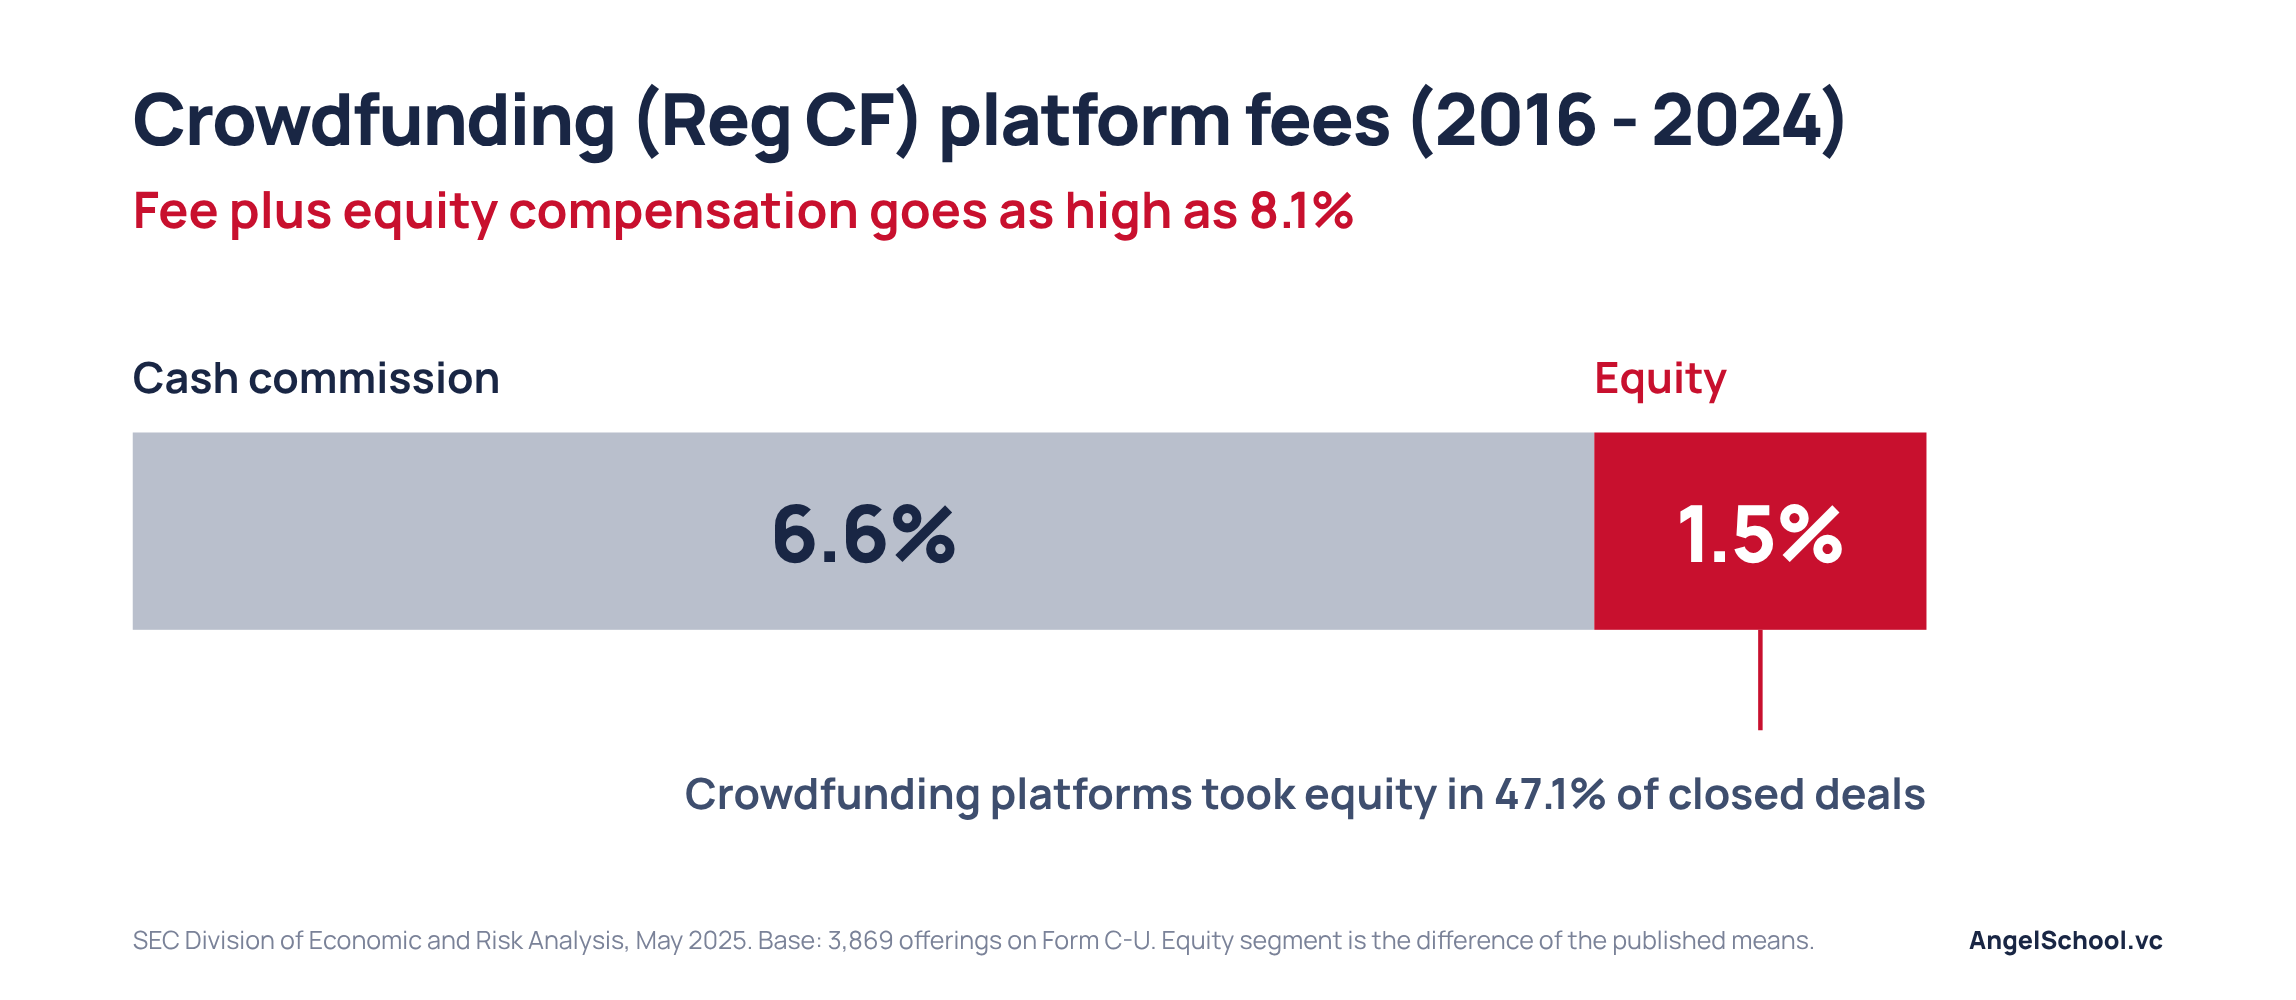
Image 1 of 2: What a Regulation Crowdfunding platform takes out of a closed offering, a 6.6% cash commission plus 1.5% in equity for 8.1% of proceeds in total, with equity taken in 47.1% of closed deals.
How Crowdfunding Platforms Monetize. The fee is paid on moving capital. Not on the company surviving, not on the deal being priced well, and not on producing a return to investors. Wefunder waives its success fee entirely when the founder brings their own lead investor.
Their incentive is simply market-making. The levers are more deals, attractive marketing and more closes. They make fees on every dollar moved, and in many cases take equity with no skin in the game and no capital at risk.
Crowdfunded (Reg CF) Startup Performance
The companies are small, young and unprofitable. This is supported by the SEC's study.
Start With How Many Raises Actually Close.
| Reg CF offerings, 2016 - 2024 | Offerings | Share of those that went live |
|---|---|---|
| Went live on a platform | 8,492 | — |
| Reported raising money | 3,869 | 46% |
| No proceeds reported | 4,623 | 54% |
| Withdrawn before completion | 990 | Excluded from the 8,492 |
SEC Division of Economic and Risk Analysis, May 2025. The SEC notes that some offerings closed successfully without filing a Form C-U carrying proceeds detail, so 3,869 is a lower bound.
Notice that more than half the offerings that went live reported raising nothing at all, and a further 990 were pulled before they got that far. The average successful raise was $346k ; the median was $113k. These raises are not 'needle movers' compared to early-stage venture rounds.
Across those 8,492 offerings, the median company had just under $80k in total assets, $13k in cash, $60k in debt, $10k in revenue and 3 employees, and had been formed 2.4 years earlier. Only about 1 in 7 had ever posted a net profit. The median had a loss of around $32k.
How Did They Perform?
| Outcome, 2016 - 2024 | Companies | % of those that raised |
|---|---|---|
| IPO | 8 | 0.25% |
| Acquired | 71 | 2.2% |
| Went on to raise venture capital | 110 | 3.4% |
Every row: SEC Division of Economic and Risk Analysis, May 2025. Base is the 3,253 companies that reported proceeds on Form C-U.
Less than 1 in 40 reached any liquidity event within 9 years, and less than 4% attracted institutional capital afterwards. 8 companies out of 3,253 made it to an IPO.

Image 2 of 2: Of the 3,253 Regulation Crowdfunding companies that reported raising money between 2016 and 2024, 110 received venture backing and 79 reached an exit, of which 71 were acquisitions and 8 were initial public offerings.
What the Data Says. Published failure-rate estimates for Reg CF range from 2.9% to about 75% depending on who is counting. This pretty much tells us that no one knows. What the SEC data does show is that 97.6% of the companies that raised reached no exit at all, neither a failure nor a return. They are in purgatory.
Why We Think Crowdfunding Platforms Are Flawed
These Platforms Are Brokers. They take their pound of flesh while delivering very little of value, on deals that are adverse-selection heavy.
What Gets Listed. The listings skew toward simplistic, easy-to-understand businesses in crowded spaces, heavily consumer. Set aside that it is off-thesis for us ; these are extremely hard businesses to get a venture outcome from.
I've Never Written a Check on a Crowdfunding Platform Deal. I've looked at Wefunder and Republic deals at various points between 2022 and 2025. I did not find anything that I thought met my bar as a venture-worthy investment.
Most of what exists on a crowdfunding platform skews too heavily towards consumer businesses, which I'm skeptical of in terms of reaching venture outcomes. With the right deal, I would not take issue with the fee structure.
A company with a credible seed round and a fighting chance to find a lead investor does not pay 8% and take on a public filing obligation to raise $113k. Our view is that with rare exceptions, what makes it to crowdfunding platforms could not raise private venture funding. Adverse selection is the norm, not the exception.
54% of offerings also failed to raise anything. I for one would not want to back an early-stage company that isn't properly capitalized.
At $100 - $300, nobody can rationally spend 8 hours on diligence. The cost of looking exceeds the size of the position, so decisions get taken on gut feel and first impressions.
What Scaling on These Incentives Produced. FINRA censured and fined Wefunder $1.4 MN. Across 39 separate offerings the platform raised roughly $20 MN more than Reg CF limits permit — FINRA, AWC No. 2021071940801, May 2022.
It sent over a million emails to investors recommending and soliciting investments. FINRA found the platform's statements about lead investors were "exaggerated and misleading", and that the firm "took no action to verify whether those statements were true". Two Reg CF escrow accounts were left dormant holding roughly $290k.
The conduct ran May 2016 - December 2021. Wefunder settled without admitting or denying the findings, and the remediation undertaking is complete. This is not a live proceeding. It is what the incentive produces at scale: a broker paid on volume, moving more volume than the rules allowed.
Accreditation Requirements in Crowdfunding. Republic states that accredited investors face no investment limits at all on Reg CF offerings, and Wefunder runs accredited-only Reg D funds alongside its Reg CF business. What separates Reg CF from Reg D is check size and screening, not investor accreditation.
Angel Investing Platform Fees
Every figure below comes from the platform's own published terms or its regulatory filings, verified at source on 11 October 2026. Terms change ; check them before you wire.
| Platform | Regulation | What you pay at entry | What you pay at exit | Who screened the deal |
|---|---|---|---|---|
| Wefunder | Reg CF | 2% by ACH or wire (min $8, max $150) ; 5.5% + $2 by card, no cap | Nothing. No carry on Reg CF | Open marketplace, minimal screening |
| Republic | Reg CF, plus an accredited deal room | 2.5% admin fee (min $5, max $250), varies by offering | Deal room terms are not published | More selective than an open portal |
| StartEngine | Reg CF and Reg A+ | 3.5% on top of the share price, capped at $700 | Nothing disclosed on Reg CF | Semi-curated |
| AngelList | Reg D | Nothing to browse ; vehicle costs pass through | 20% carry is standard, set by the lead, not by AngelList | The lead, and only the lead |
| OurCrowd | Reg D | Not published. $10k minimum | Management fee and carry per deal, not published | Its own investment team, co-investing |
| Clarity (formerly Hiive), Forge | Reg D secondaries | 2 - 5% buyer commission ; 7.5% on Clarity private funds | Not applicable | Not applicable. You are buying existing shares |
| A lead-run syndicate, including ours | Reg D | ~6%, covering the SPV and the lead's management fee | 20% carry | The lead, who has to live with it |
Wefunder, Republic and AngelList help centres, accessed 10 October 2026. The last row is ours.
Notice that low-fee, carry-free crowdfunding also does no screening. Carried interest applies when a responsible counterparty exists.
Accessing AngelList. AngelList is tightening investor admissions. This runs through Meridian, and requires an application covering how you qualify, what other qualifications you hold, and your history of private market investments. A GP can invite you into a specific deal without it. The point is, there is a hurdle for entry beyond simply accreditation, which many are unaware of.
Crowdfunding vs SPV Economics
Syndicate economics are unequivocally more expensive. The question is: "Is the price of entry worth it?"
A $25k check on Wefunder takes $150 and nothing on exit. A syndicate SPV takes $1,500 in fees and 20% carry.
In other words, a syndicate has to yield ~24% higher expected value to make sense. That's the determination you need to make.
Back to 1st Principles. Go back to the SEC tables above. Fewer than 1 in 40 of the companies that raised on Reg CF reached any liquidity event. The fee drag is a quarter of an upside that, on that base rate, 97.5% of those companies never produced.
The entry fee is the wrong variable to optimize. Selection decides whether there is a return at all. Fees only decide how much of it you keep.
What Our LPs Pay, Across 25 Syndicates. Roughly 6% in fees at entry, covering the SPV and the syndicate lead's management fee, plus 20% carry on the gain.
That is the bet described above, and I'd be willing to underwrite it.
Do Syndicates Deserve 20% Carried Interest?
If an LP can put $300 into a Wefunder campaign and pay no carry at all, why would they put $25k into an SPV at 6% and 20%?
Well, there's no free lunch. Both are fundamentally different assets and should accordingly be treated differently. One is a company that reached an open marketplace, screened by a broker paid on the close. The other is a deal a named lead sourced, negotiated and put their own money into, alongside institutional investors.
Syndicate LPs pay 20% carry to compensate the lead for deal sourcing, diligence, piecing the deal together, and investor reporting for the life of the investment. Carried interest is how syndicate leads get compensated. It maximally aligns them with LPs in exactly the way that Reg CF does not. Crowdfunding platforms are paid on the raise, which is not attached to a return outcome at all.
Reg CF and Syndicate Platforms: Which Should You Choose?
Reg CF only makes sense if you are comfortable writing small checks and enjoy looking at early-stage companies. There is a significant amount of adverse selection built in, and we generally do not advocate for it.
Syndicate Platforms. Platforms like AngelList aggregate different syndicates. Accreditation is required, in addition to other criteria, in order to access them. Whether you should deploy capital into a syndicate on AngelList or anywhere else comes down to their dealflow quality and their diligence skill. That is what earns them their carried interest. The simple thing to do is to ask for their diligence on a recent deal and see if it meets your bar.
Pre-IPO Secondaries. Direct secondaries are almost impossible for early-stage individual investors to access, because of the capital scale required. These are broker-arranged blocks that start around $1 MN and sit with institutions. Any access you are offered below that will be on multi-layer SPVs, with fees on fees and carry on carry.
The marketplaces are a different route. Clarity, formerly Hiive, sets a standard minimum of $25k and Forge $100k on direct trades, and both charge the buyer 2 - 5% at entry. Accreditation is required either way. We cover pre-IPO secondaries separately.
Standalone Syndicates (Like Ours). The point of a syndicate, whether standalone or on a platform like AngelList, is deal curation and portfolio control. Each syndicate lead sources their own dealflow, does their own diligence, and makes recommendations to investors. The investor retains control to invest in whatever deals they want, subject to a minimum check.
If you want the mechanics underneath all of this, from sourcing to diligence to deal structure, check out AngelSchool.vc's Masterclass: Venture for Angel Investors. It's a free resource we built for the venture community.
This article describes US federal securities law and general market practice as at October 2026. Platform terms change without notice, the INVEST Act is not law, and nothing here is legal, tax or investment advice.
Frequently Asked Questions
What Is the Minimum to Invest on AngelList?
There is no single platform-wide minimum. AngelList states that some deal minimums go as low as $1,000, and the lead sets the number for each vehicle, so the figure moves deal by deal. Accreditation is required, and broad access additionally needs an approved Meridian application covering your qualifications and your private-market history. The widely repeated "AngelList: $1,000 minimum" is wrong as a platform-wide claim.
Do Angel Investors Actually Make Money?
Some do, and returns are driven entirely by a handful of outliers rather than by the average deal. The SEC's outcome data for Reg CF companies is in the body above and it is sobering. For Reg D syndicates, no citable source publishes net returns to individual angels at seed stage, so treat any headline IRR you are shown as unrealized and marked by whoever is showing it to you.
How Often Does a Reg CF Raise Actually Close?
Less than half the time on the published data. 3,869 of the 8,492 offerings that went live between 2016 and 2024 reported raising money, and a further 990 were withdrawn before completion. The SEC notes that some successful closes never filed proceeds detail, so treat 46% as a floor rather than a verdict.
Can I Use a Crowdfunding Platform if I Am Accredited?
Yes, and with no investment limits. Republic states this directly, and Wefunder runs accredited-only Reg D funds alongside its Reg CF business. The annual caps tied to income and net worth apply to non-accredited investors, not to you. What separates the two regimes is check size and screening, not your accreditation status. Whether you should is a different question, and the body of this article is the long answer.
What Is the Difference Between Carry and a Platform Fee?
Carry is a share of profit, paid only if the deal makes money. A platform fee is cash, paid when you invest, whether or not it ever works. Wefunder charges the latter and none of the former on Reg CF ; a syndicate lead charges mostly the former.
Will the Accredited Investor Rules Change?
Possibly, and not yet. The INVEST Act would create a free SEC exam pathway to accredited status and index the existing wealth thresholds to inflation. It passed the House in December 2025 and has not moved in the Senate. Watch it ; don't plan around it.
Is a Platform or a Syndicate Better for a 1st Check?
The question is who screened the deal and whether you trust their judgment. Answer that first and the path follows. On a crowdfunding platform the screening is a broker paid on the close ; in a syndicate it is a named lead who put their own money in. Neither is automatically better, but only one of them has someone to answer for the deal when it goes wrong.
How Much Diligence Do These Platforms Actually Do?
Reg CF crowdfunding platforms do not do investment diligence. They carry a regulatory obligation to take measures against fraud, which is not the same thing. Anything you are shown comes from the company itself, and it is skewed with positive bias. For syndicates it depends on the lead. Ask for their recent diligence on a deal and decide if you trust their skill.
About AngelSchool.vc

AngelSchool.vc is the ultimate Accelerator for Angel Investors - from 1st check to leading syndicates as ‘Super Angels’. We give venture investors world-class training, a global community AND build their track record as a member of our Investment Committee (IC).
The AngelSchool.vc Syndicate is backed by 1500+ LPs and deploys $MNs annually. Subscribe here for exclusive dealflow.