A SAFE and a convertible note are ways for an angel to invest in a startup and receive equity later, when it converts at the next priced round based on a valuation cap or a discount off the next equity round’s price. The convertible note is a debt instrument since it carries interest and a maturity date, whereas the SAFE has neither.
Almost every comparison of the two is written from the perspective of founders raising capital, and how it impacts their ownership.
This one is written for the angel investor writing the cheque, because on these terms what's good for the founder comes at the investor's expense.
TL;DR
- Do angels get to choose between a SAFE and a note? Almost never. You're a 'price taker' in a round where founders or a lead investor have set terms. The one lever angels are always in control of is walking away.
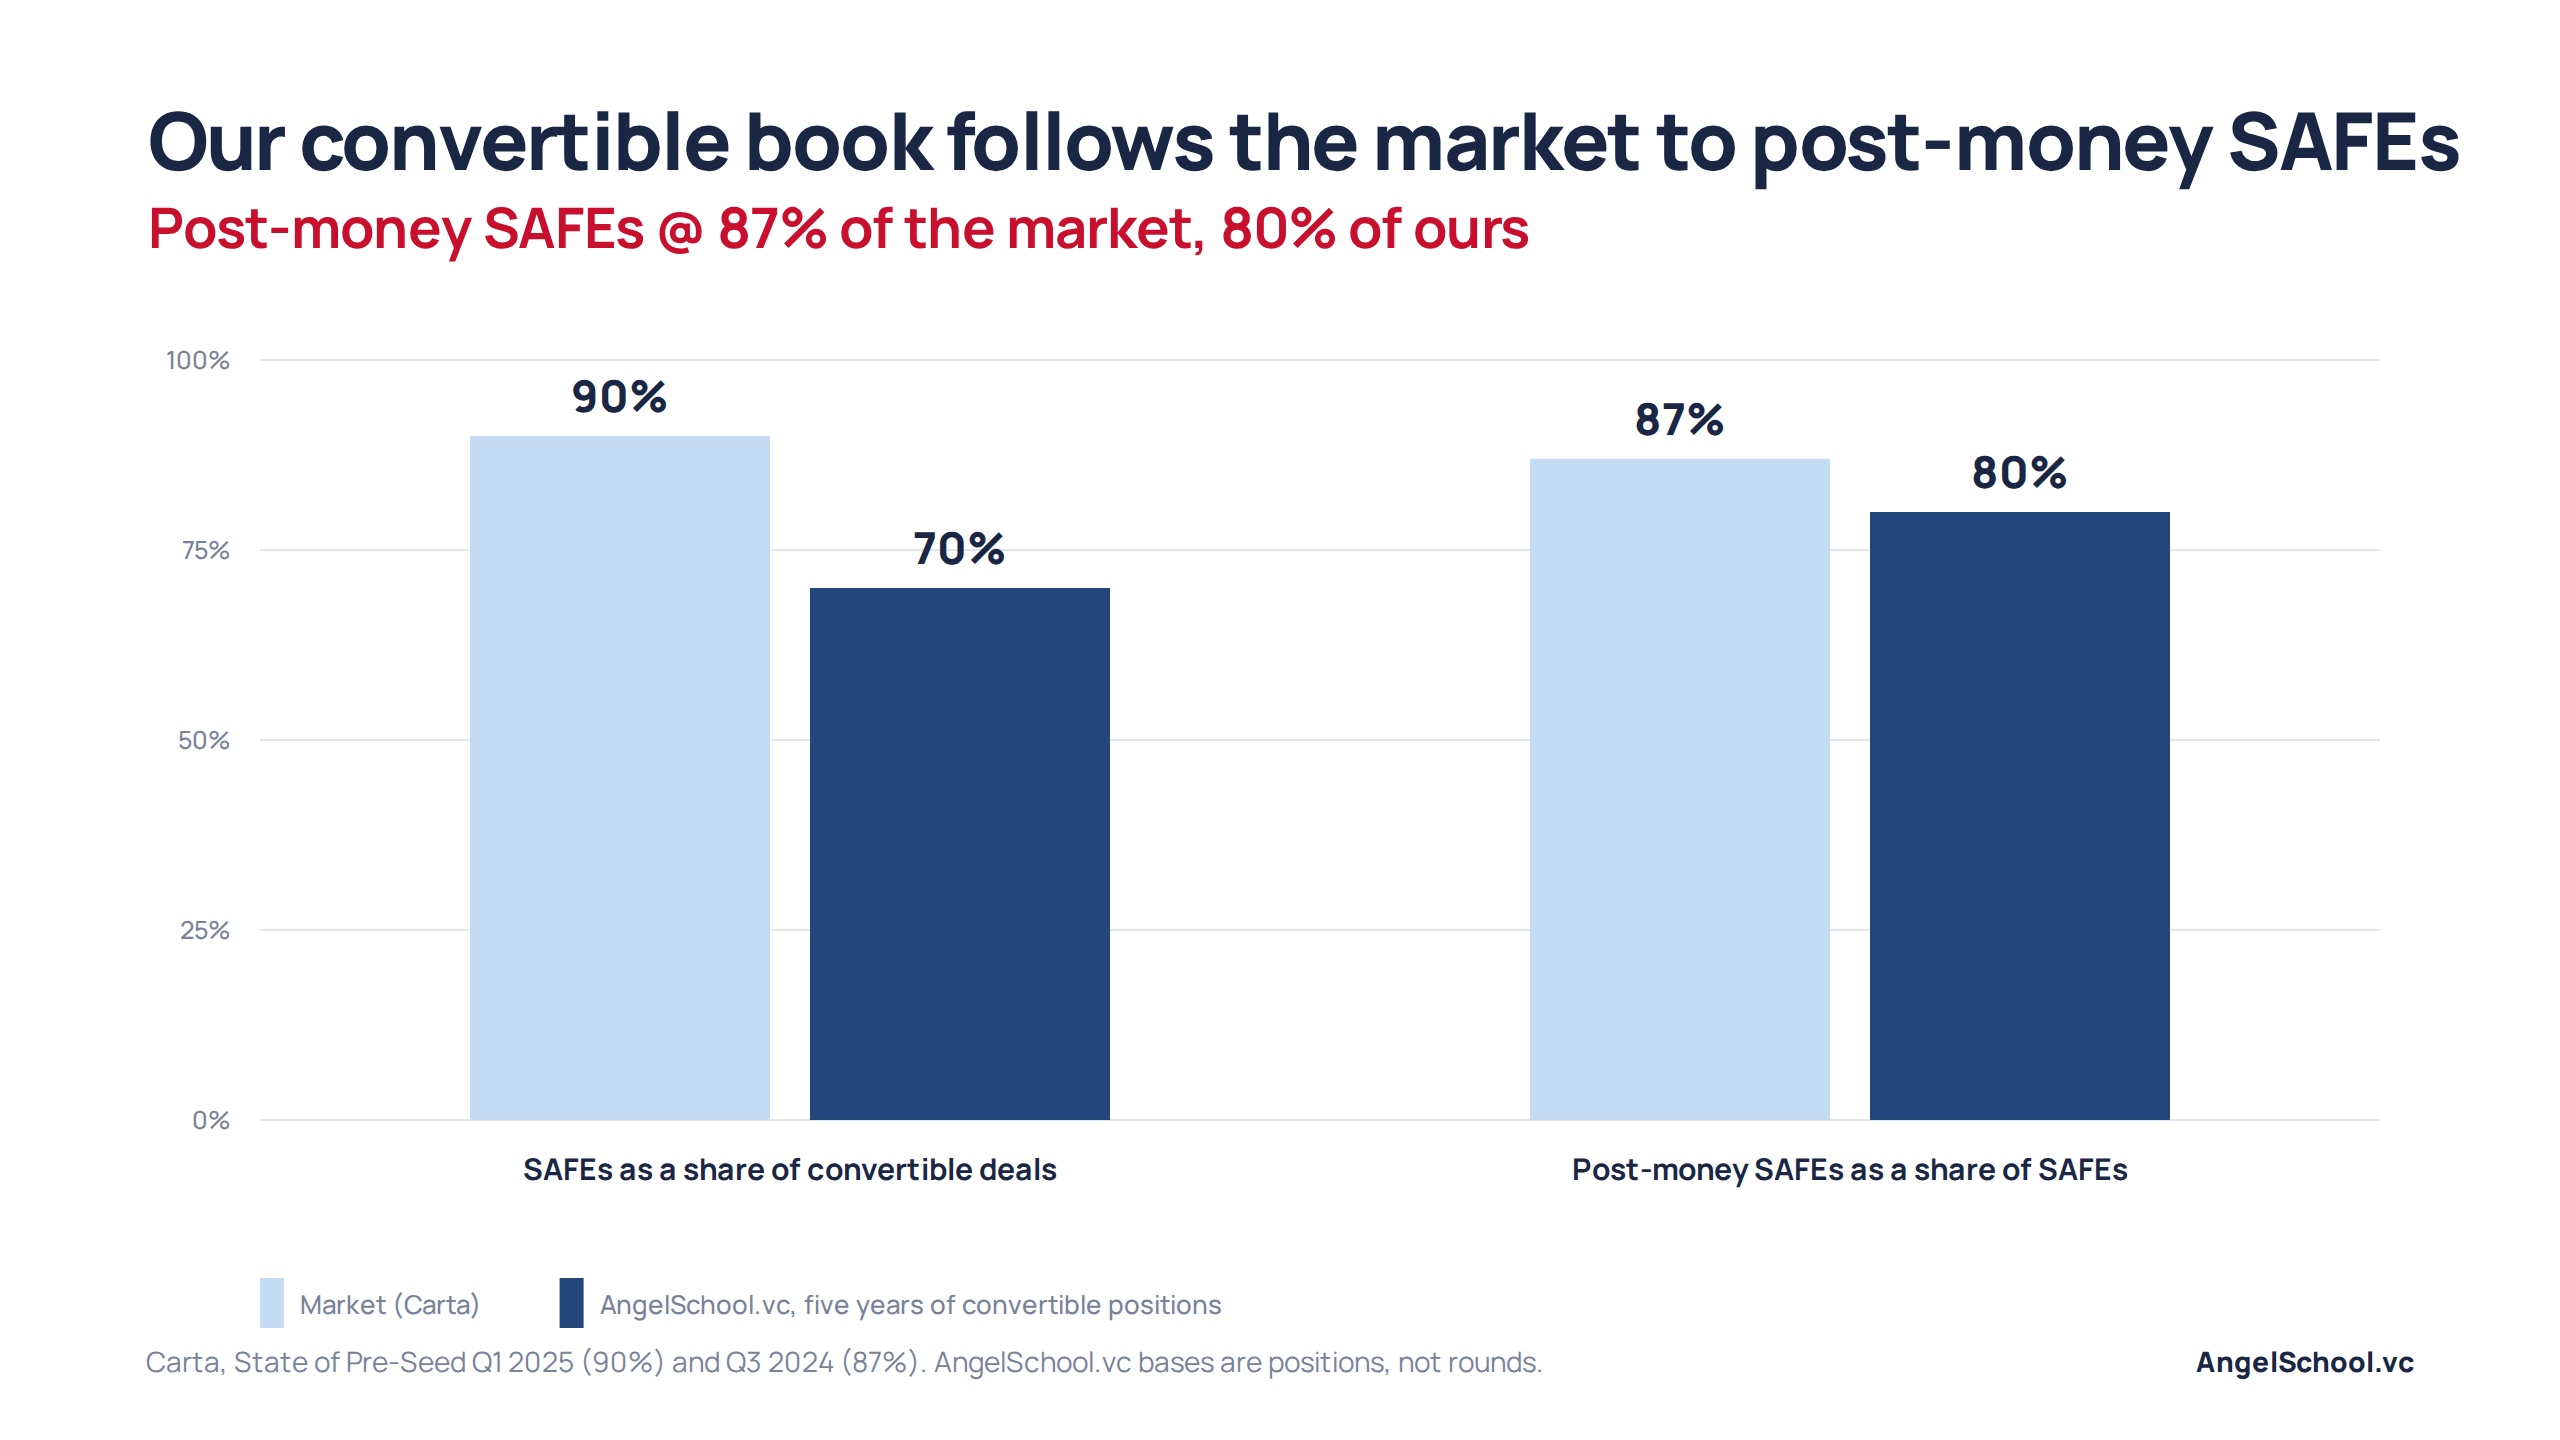
- Which is more common? SAFEs were a record 90% of pre-seed rounds, and 87% of SAFEs were post-money SAFEs — Carta, Q1 2025 and Q3 2024.
- If you could choose, which is best for the investor? A post-money SAFE first, a pre-money SAFE second, a convertible note last.
- Should you accept an uncapped SAFE or note? They only make sense in very limited situations. If one term has to go, keep the cap and give up the discount ; 91% of US SAFEs in 2024 carried a cap — Carta, 2024.
- Does note interest help you? Barely. At ~7% a year it adds ~14.5% over two years, every investor in the note gets the same, and the founders pay for it in dilution.
- When should you invest in a convertible note or SAFE? Ask yourself one question: “Do you expect it to convert at the cap instead of the discount?” The cap improves your upside. If your instrument converts on the discount, the company is in a downside scenario.
What a SAFE and a Convertible Note Actually Do
Both instruments defer the valuation question. You hand over cash today, and the instrument converts into shares at the company's next priced round, at whichever of the valuation cap or the discount gives you the lower price per share. That is, if it happens at all.
A convertible note has debt characteristics. It accrues interest, typically around 7% a year in the notes we've seen, and it carries a maturity date, usually 24 months. For the instrument on its own, we cover what a convertible note is and how it works separately.
A SAFE, a Simple Agreement for Future Equity, carries no interest or maturity. If the company is sold before it converts, investors receive the greater of their money back or its as-converted proceeds. In a wind-down, they get their money back after creditors but ahead of common stockholders — Y Combinator, 2018. Realistically, very little is returned.
Whether it’s a convertible note or SAFE, having both a cap and discount is the ideal outcome since it gives investors optionality in both up and downside scenarios. A maturity date puts an expiry on that optionality. That’s the biggest difference for investors risking capital.
SAFE vs Convertible Note: The Difference in One Table
Read each row twice, once as the founder and once as the angel.
| Term | SAFE | Convertible note |
|---|---|---|
| Legal form | A contract for future equity | Debt |
| Interest | None | Accrues, ~7% a year in the notes we've seen |
| Maturity | None | Usually 24 months |
| Converts at | The next priced round If acquired first: the greater of your money back or your as-converted proceeds | The next priced round, or as the note provides at maturity If acquired first: principal plus accrued interest in cash, sometimes with a premium or an option to convert |
| Pro rata rights | Pre-money SAFE: built in ; Post-money SAFE: requires side letter | No standard form ; depends on the note |
| If the company winds down | Money back, behind creditors, ahead of common shares | Unsecured debt: behind secured lenders, ahead of SAFEs and all shareholders |
| The founder's view | Faster, cheaper, no debt on the balance sheet | A deadline and a debt on the books |
| The angel's view | The option stays open ; a post-money SAFE fixes your ownership | The maturity caps the option, and the interest adds little |
Notice that the angel's view goes one way: there's no clock on a SAFE, so the option stays open. It’s less clear cut for founders ; which instrument suits a founder depends on the round.
Notes outrank SAFEs if the company is sold or winds down. They are unsecured debt that repay principal plus accrued interest in cash on an acquisition before conversion — Penn Law Entrepreneurship Legal Clinic, convertible note template.
The SAFE ranks behind creditors, including outstanding convertible notes — Y Combinator, 2018. In an early-stage wind-down, neither usually gets much back so we don’t consider convertible note repayment as a material advantage.
What investors should prefer, the ranked answer.
One. The post-money SAFE. No maturity, and your ownership is fixed at the cap until the priced round, whatever other SAFEs the company raises after yours.
Two. The pre-money SAFE. No maturity either, but every SAFE the company raises after yours dilutes you before conversion.
Three. The convertible note. The maturity puts a clock on your conversion option, and the interest doesn't make up for it.
Why You Will Almost Never Choose the Instrument
Most angels are 'price takers'. You’re usually a small cheque writer into a round whose valuation, instrument and terms were set by the founder or lead investor before you entered the conversation. Angel investors lack leverage in the face of large institutional funding rounds.
In almost every deal, you’re stuck with the terms and instrument.
The one lever that you always have is the right to walk away. Be comfortable using it!
What we actually invested in, across five years of deal making. Of our investments in convertible financings, roughly 70% were SAFEs and 30% were convertible notes. Of the SAFEs, 80% were post-money SAFEs, and that share has risen as it is increasingly adopted.
It’s also a reflection of where we deploy capital. We do more deals in the US than other parts of the world. In the US, the post-money SAFE has nearly become the de facto instrument for convertible financings.
That matches wider market data. SAFEs made up a record 90% of pre-seed rounds on Carta in Q1 2025, and 87% of SAFEs in Q3 2024 were post-money SAFEs — Carta, Q1 2025 and Q3 2024.
The Maturity Date Puts an Expiry on Your Upside
The whole case for a convertible instrument is optionality. The cap and the discount allows conversion into whichever is more favorable for the investor. This rewards angel investors for taking a risk when an early-stage company cannot be priced with confidence.
A maturity date caps that optionality to a time window. If the company hasn't raised its priced round within 24 months, the note hits its deadline, and investors lose the option, unless it is extended based on renegotiations.
Redemption is a right you won't use. A maturity date technically lets investors redeem the note for cash, but it almost never happens. An early-stage startup that hasn't reached its next round won't have the liquidity to repay you, and forcing redemption forces a default, at the investor’s detriment.
In practice the note converts or gets extended by agreement. The maturity rarely protects you ; it forces a renegotiation at the moment the company, and you, have the least leverage.
This is important when fundraising is taking longer. The median gap between a seed round and a Series A reached 616 days in Q2 2025, up from about 493 days two years earlier — Carta, Q2 2025. That's roughly 20 months against a 24-month maturity, and the median only counts the companies that did raise.
Outside sectors like AI, a lot of startups are having trouble reaching their next round. A maturity date turns that struggle into a deadline, and it simply doesn’t make sense for investors!
Why Note Interest Is the Wrong Thing to Focus On
In the notes we've seen, interest typically runs around 7% a year. Compounded over a 24-month maturity, that's about 14.5% more principal converting into shares.
The interest rate on a note is often pitched by founders as a benefit but it really doesn’t matter, for two reasons.
One. The magnitude is wrong. Venture investments are a play for multiples returns, not for percentage points. A 14.5% top-up on your principal isn’t material when it should return your capital many times over or goes to zero.
Two. All investors get interest. It’s likely that every investor in every convertible note sold by a company, before and after you, gets interest as well. That means you gain nothing relative to the others in the round. It adversely impacts founders, who pay for that interest from their slice of equity.
The point is, note interest adds dilution without adding a meaningful advantage for investors, so they don’t really make sense.
Uncapped (Discount Only) Convertibles
In a perfect world, every convertible instrument you invest in should have both a cap and a discount. If you had to make a tradeoff, keep the cap and give up the discount.
Uncapped, discount-only SAFE or notes rarely make sense. They cap your upside at the discount. Your gain at conversion is 1 ÷ (1 − discount). At the typical 20% discount, that's 1.25x return to compensate you for the time between investment and conversion, and carrying the risk of the company not raising that next equity financing, or perhaps on lousy terms.
That’s the difference between you and the investor who entered in the priced round.
Exhibit A. You invest $1 MN on an uncapped post-money SAFE at a 10% discount. The company later raises its priced round at a $10 MN pre-money valuation: the lead invests $2 MN and requires a new 10% option pool, set inside the pre-money. Compare that with holding your $1 MN back and investing it alongside the lead in the round, which makes the round $3 MN.
| Uncapped SAFE before the round | $1 MN in the priced round | |
|---|---|---|
| Round size | $2 MN | $3 MN |
| Post-money valuation | $12 MN | $13 MN |
| Your ownership | 9.26% ($1.11 MN / $12 MN) | 7.69% ($1 MN / $13 MN) |
| Value at the round price | $1.11 MN (1.11x) | $1.00 MN (1.00x) |
| Lead's ownership | 16.67% | 15.38% |
| Option pool | 10.00% | 10.00% |
| Founders | 64.07% | 66.92% |
Notice that the SAFE investor comes out ahead at 9.26% ownership against 7.69% if participating in the priced round. While part of that is the 10% discount, your $1 MN was already in the company, and sits in the pre-money bucket before the equity investor’s capital. The option pool doesn't touch you in either case, because it's set inside the pre-money and the founders pay for it.
That 1.57% ownership benefit might have taken 12 - 24 months to convert. There’s also always the possibility that the equity round doesn’t happen at all!
The way to think about this is that the uncapped, discount only instrument only makes sense if you have a >90% confidence (1 ÷ 1.11) the startup will complete the equity financing, AND the expected time to that event is worth your money being tied up.
If the round was priced at $30 MN pre-money instead, the uncapped SAFE would still be worth $1.11 MN. Having a cap is what would have captured that upside.
The market mostly agrees. Here's how US SAFEs were structured in 2024.
| Structure | Share of US SAFEs, 2024 | Source |
|---|---|---|
| Valuation cap only | 61% | Carta, 2024 |
| Cap and discount | 30% | Carta, 2024 |
| Discount only | 8% | Carta, 2024 |
| Neither | 1% | Carta, 2024 |
9 out of 10 SAFEs carry a cap. Uncapped instruments comprised only 9%, so when you're offered one, ask why the founder wants it, and critically assess whether the deal makes sense for you.
The takeaway is that a cap benefits investors in an upside scenario. A convertible without one limits the investor’s upside in the face of venture risk.
Pre-Money SAFE or Post-Money SAFE: Know Which One You Hold
Within SAFEs there are two forms, and the difference is who absorbs the dilution from other notes and SAFEs. With a post-money SAFE your ownership is fixed at the cap until the priced round, so additional convertible financing raised after yours dilute the founders, not you. Under a pre-money SAFE, SAFE holders are diluted alongside founders.
Exhibit B. Y Combinator's own example sets $500k on a pre-money SAFE at a $4.5 MN pre-money valuation cap against the same $500k on a post-money SAFE with a $5.5 MN post-money valuation cap, which is akin to locking in 9.09% until it converts — Y Combinator, 2018.
We extend it across a series of SAFE financings raised by the company at the same cap before its priced round, ignoring the option pool.
| Other SAFE money raised | Pre-money SAFE, $4.5 MN cap | Post-money SAFE, $5.5 MN cap |
|---|---|---|
| $0 | 10.0% ($500k / $5 MN) | 9.09% ($500k / $5.5 MN) |
| $500k | 9.09% ($500k / $5.5 MN) | 9.09% ($500k / $5.5 MN) |
| $1 MN | 8.33% ($500k / $6 MN) | 9.09% ($500k / $5.5 MN) |
| $2 MN | 7.14% ($500k / $7 MN) | 9.09% ($500k / $5.5 MN) |
Notice that the pre-money SAFE starts ahead, at 10%, and falls behind as soon as the company raises more than $500k of other SAFE money. The post-money SAFE costs you a little more on day one and then holds its line, which is exactly the protection it affords when the startup raises additional convertible financings of any form after you.
There is, however, a difference when it comes to pro rata. Pre-money SAFEs carry pro rata rights by default, and apply to the round after the one in which it converts. Post-money SAFEs require pro rata rights by way of a separate side letter, and kick in on the conversion round itself — Y Combinator, 2018.
I advise investors to always ask for pro rata rights ; it's a free option, and the worst outcome is to be told ‘No’. On a post-money SAFE, secure the right through Y Combinator's side letter template. We cover the conversion mechanics in how a post-money SAFE converts.
SAFE Stacking Tells You How the Company Raises
A company's fundraising history and its use of convertible instruments tell a story beyond simply its fundraising history. You get a sense of capital efficiency. The terms on each instrument say something about founder's demeanor when it comes to optimizing for valuation.
Datamilk: the terms told the story. Towards the end of the venture peak, we looked at an investment in Datamilk. Over a span of 11 months in 2022, they raised a series of convertible financings that aggressively increased its valuation cap from $10 MN to $70 MN.
That isn’t a problem if the metrics keep pace which wasn’t the case here. What stood out was how the founders went from post-money SAFEs to pre-money SAFEs, and cut the discount from 20% to 0% in later instruments, exactly when the rest of the market was moving the other way.
It painted a picture of founders chasing valuation aggressively, using the cap to anchor pricing in their next equity round, and shifting to less investor-friendly terms.
Sadly, they have gone out of business. Thankfully, we declined the deal because of this among other reasons.
The lesson here is that investors should watch for 'SAFE stacking'. This is a situation where a startup has raised multiple financings using convertible instruments, missed their operating targets and/or incurred higher burn than expected. They then raise yet more convertible financings to keep going.
Each new SAFE or note kicks the can down the road. It allows founders to avoid a downround that an equity round would force. They don't feel the dilution impact because the instruments haven’t converted into equity. The stack is evident when you build a pro forma cap table, and you can be sure a sophisticated institutional investor will go looking.
Conversion Dilutes Hardest in the Downside
Convertible instruments behave like liquidation preferences in one important way: the damage is asymmetric. In a downside scenario, conversion hits founder ownership much harder.
When a startup raises a priced round well above the cap, the cap kicks in. When it’s low, conversion happens at a discount to an already lower valuation. Your investment converts into more shares but ultimately at a lower equity value compared to the upside.
That’s exactly the mechanism protecting investors in a downside outcome, or rewarding them in the upside scenario.
So why should an investor care? The larger dilution impact comes out of founder ownership. That’s their problem, isn’t it?
Well, there’s no free lunch. The implications impact both the startup and investors.
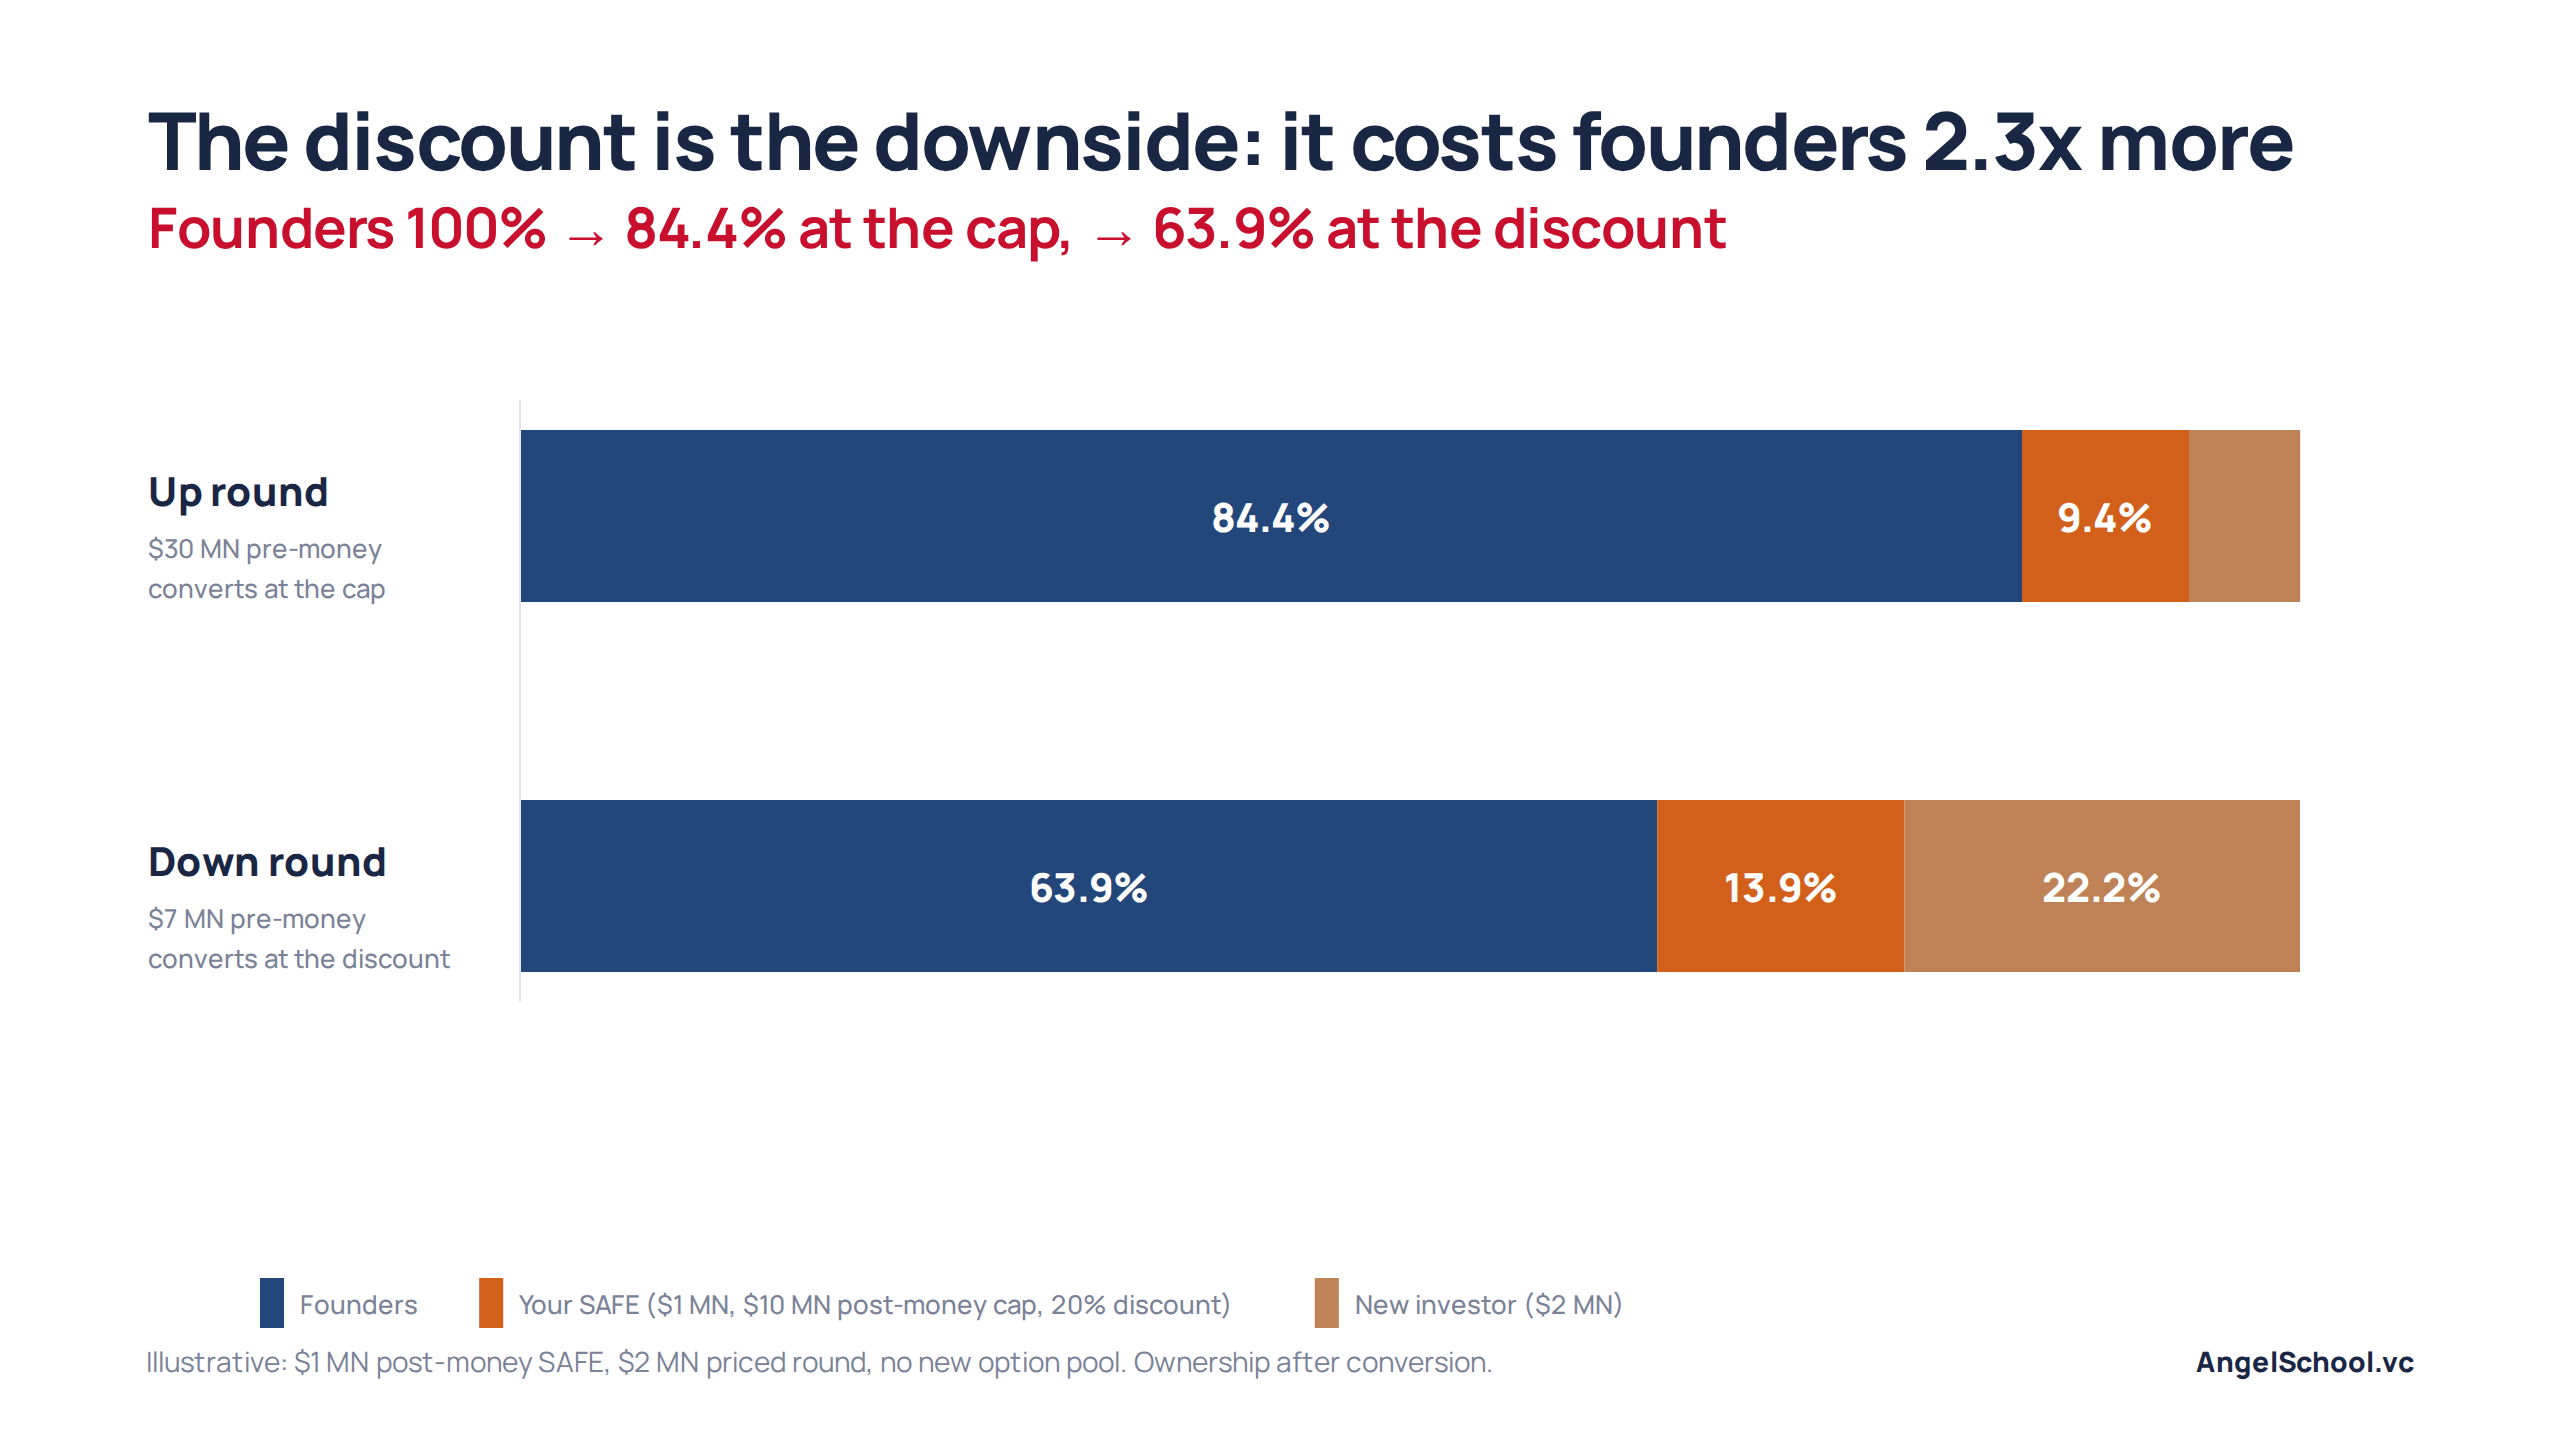
Exhibit C. You invest $1 MN on a post-money SAFE with a $10 MN valuation cap and a 20% discount.
Let’s imagine 2 scenarios. In the upside, it raises a $2 MN equity round at $30 MN pre-money valuation. In the downside, it raises the same $2 MN at a $7 MN pre-money valuation. There's no option pool in either case.
| Up round, $30 MN pre-money | Down round, $7 MN pre-money | |
|---|---|---|
| SAFE converts at | The cap: $10 MN | The discount: $5.6 MN (20% off $7 MN) |
| Your ownership | 9.38% (10% × $30 MN / $32 MN) | 13.89% ($1.25 MN / $9 MN) |
| Value at the round price | $3.00 MN (3.0x) | $1.25 MN (1.25x) |
| New investor | 6.25% ($2 MN / $32 MN) | 22.22% ($2 MN / $9 MN) |
| Founders | 84.38% | 63.89% |
| Founder dilution from the round | 15.6% (100% → 84.38%) | 36.1% (100% → 63.89%) |
Notice that the same $2 MN round costs the founders 36.1% of ownership at the discount, against 15.6% at the cap.
That's 2.3x higher dilution from a lower valuation alone. The SAFE takes 13.89% instead of 9.38%, and the new money buys more ownership.
For angel investors, the discount is a downside cushion, not a win. You might own more in terms of equity percentage, but your stake at $1.25 MN is worth a lot less than $3 MN at the cap.
It is equally plausible that the convertible never converts because of this. An incoming VC will look at the startup’s funding history, and model out founder ownership on a pro forma basis. In minutes, they’ll reach a decision that hurts existing investors.
One. The cap table is broken. The company is deemed uninvestable. It is unable to raise additional capital, and goes to zero.
Two. The investor recaps the founder. In a marginal case the incoming investor likes the company, but not at this price and the cap table as it stands. They enforce a recapitalization.
A digital health company that ended in a recap. We made a seed investment in a digital health company that went on to raise a $25 MN equity round led by a VC firm. That converted our instrument into equity.
As is often the case in medtech, long sales cycles, regulatory approvals and other barriers made GTM a slow difficult slog. A relatively inexperienced founder equipped with a bag of cash, facing pressure to grow, spent it inefficiently. The company burned through much of that capital without much revenue progress, then had to cut burn sharply and simultaneously raised more convertible financings to prolong runway.
The result was a broken cap table and a timeline that put them in a corner. New investors saw something in the technology, but also had leverage against the cap table.
They forced a recap which involves setting up a NewCo, injecting capital for 20 - 30% ownership, and giving founders 50 - 60%. The original investors received the rest.
Their earliest backers, who had been in the company longest, were diluted down to around 10%. Their preferred shares were converted to common in the NewCo, so they dropped down the repayment stack as well.
What You Can Actually Do: Model the Cap Table After Conversion
Angels rarely, if ever, get a choice in the type of instrument. It’s irrelevant to dissect which is better since you almost never get to decide.
If you do… Take a SAFE over a convertible note, because there's no maturity which lets you retain conversion optionality. Of the SAFEs, a post-money SAFE is preferable to a pre-money one ; it offers far better dilution protection. The scenarios where you would ever accept a discount only, uncapped instrument are few and far between. I might consider it for an existing portfolio company, but never for founders without a prior relationship.
Know what to ask for. Put yourself in the position of an incoming investor: when all of these instruments convert, would I still back this company?
If the answer is no, then walk away. We walk through the mechanics in how to build a pro forma cap table.
What founder ownership should look like. When we evaluate a pro forma cap table, we compare founder ownership after each round against the benchmark below. It's our generalized view of founder holdings post-round at each stage, within ±5%.
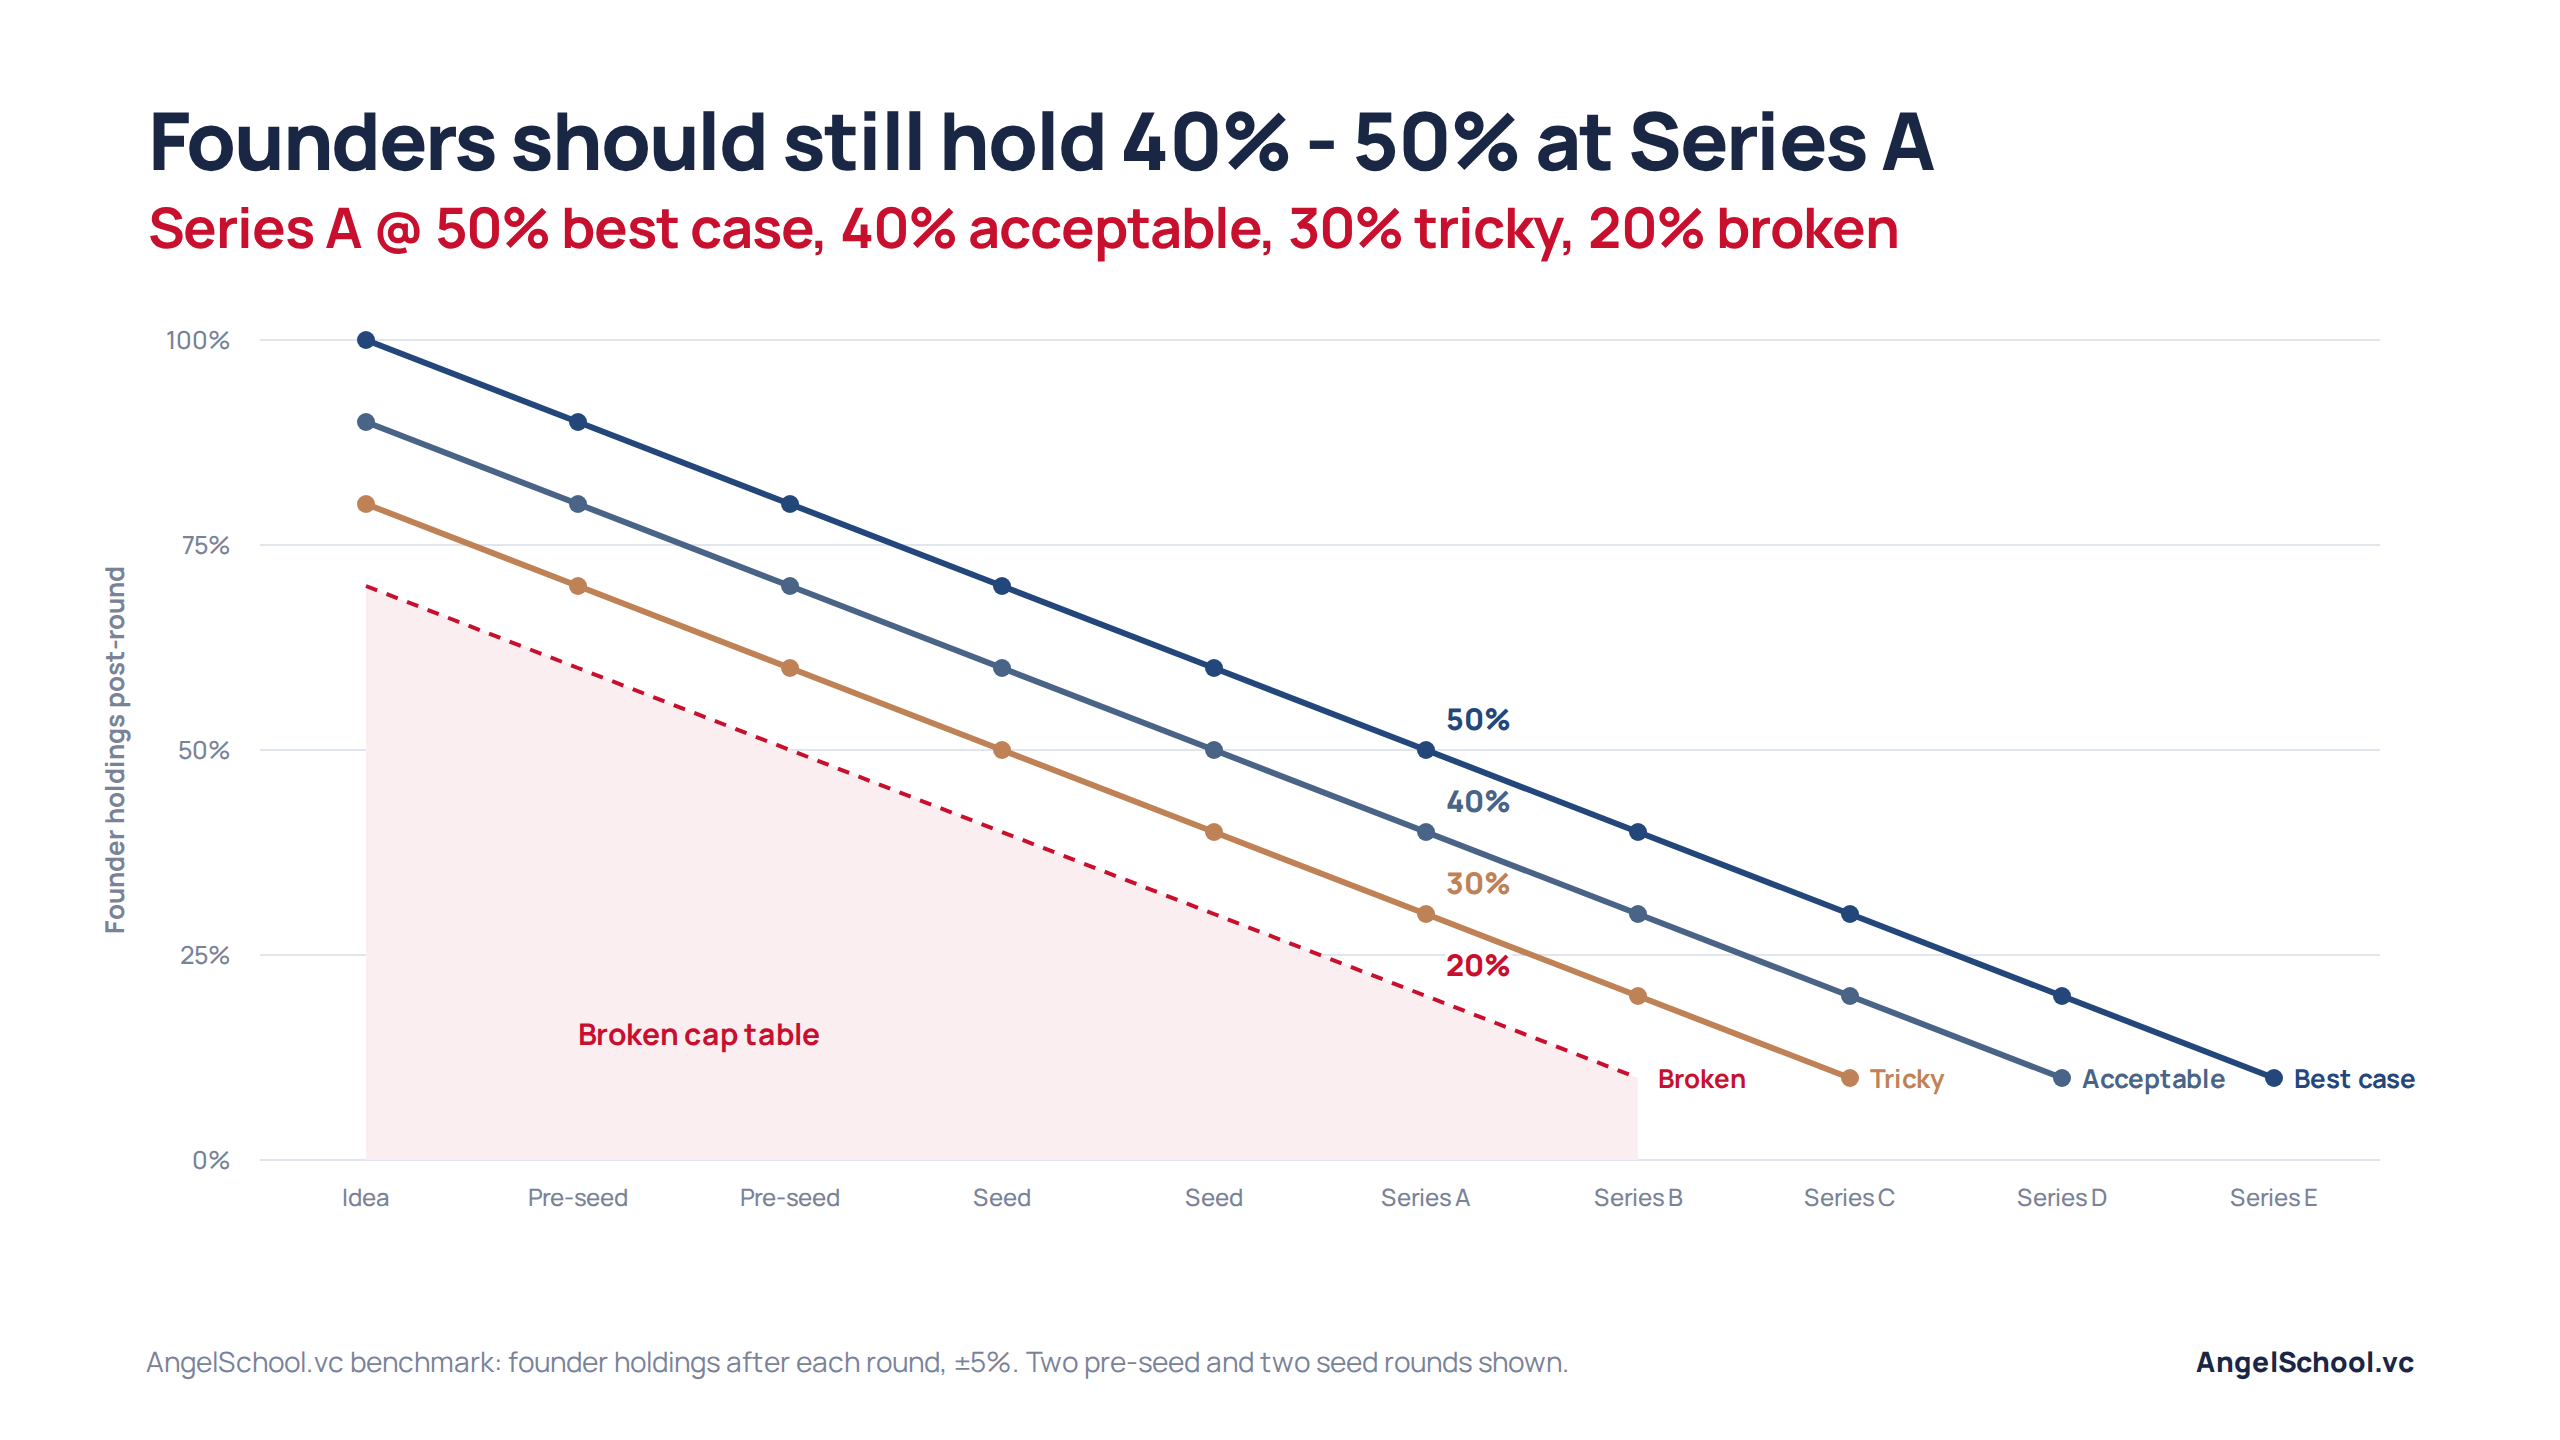
Notice how quickly a cap table moves from acceptable to broken. At Series A, founders holding 50% is a best case and 40% is acceptable ; 30% is tricky, and at 20% or below we treat the cap table as broken. The bands are a guide, not a formula ; they tell you where to look harder.
All of this is secondary to fundamental due diligence. Your SAFE or note only converts to equity if the company is doing well and is able to secure additional funding. If it isn't, it doesn’t matter. It’s the same lens we apply to liquidation preferences.
If you're looking to level up your angel investing and VC skills, check out AngelSchool.vc's Masterclass: Venture for Angel Investors.
This article describes general US market practice for SAFEs and convertible notes. Terms vary by document and jurisdiction, and nothing here is legal or tax advice.
Frequently Asked Questions
What happens if a SAFE never converts?
If the company is sold, the SAFE pays the greater of your money back or your as-converted proceeds. If it fails, you're entitled to your money back, behind creditors but ahead of common stockholders — Y Combinator, 2018.
If the company never raises a priced round and never sells, the SAFE simply stays outstanding. There's no maturity, so nothing forces conversion to equity.
What are the disadvantages of buying a convertible note as an investor?
The maturity date and the interest, both of which look like protections and mostly aren't. The maturity puts a clock on your conversion option, and the interest is paid to every investor in the note, so it gives you no advantage over anyone else. In fact, that interest adds to founder dilution which risks the cap table structure.
Do SAFEs give investors pro rata rights?
The pre-money SAFE does by default whereas post-money SAFEs do not. On a post-money SAFE, pro rata comes through an optional side letter, which Y Combinator publishes as a template. Angel investors should always ask for pro rata rights, whether they get it or not.
What happens when a convertible note reaches maturity?
It converts your investment to equity, unless it’s extended by agreement. The note technically lets investors demand repayment, but an early-stage startup that hasn't reached its next round is unlikely to have the cash, and forcing repayment forces a default that drives your investment to zero.
Is a post-money SAFE better for investors than a pre-money SAFE?
Yes, on balance, the post-money SAFE is advantageous to investors in terms of dilution protection when the company raises additional convertible financings after yours. A post-money SAFE fixes your ownership at the cap until the priced round. Pre-money SAFEs are diluted by every convertible financing that follows. In Exhibit B the pre-money SAFE falls from 10% to 7.14% while the post-money SAFE holds at 9.09%.
Is an uncapped SAFE bad for investors?
Yes, they are generally disadvantageous to investors which explains why they are infrequently used. An uncapped SAFE limits your upside to the discount. On a typical 20% discount, that’s 1.25x. Exhibit A works it through. Only 9% of US SAFEs in 2024 had no cap — Carta, 2024.
How are SAFEs and convertible notes taxed, and do they qualify for QSBS?
That's a question for your own tax adviser, and any article that gives you a confident single answer is overreaching. QSBS treatment under Section 1202 of the Internal Revenue Code depends on the company meeting its qualifying conditions, and how each instrument affects your holding period turns on facts we can't assess here. We aren't tax advisers.
About AngelSchool.vc

AngelSchool.vc is the ultimate Accelerator for Angel Investors - from 1st check to leading syndicates as ‘Super Angels’. We give venture investors world-class training, a global community AND build their track record as a member of our Investment Committee (IC).
The AngelSchool.vc Syndicate is backed by 1500+ LPs and deploys $MNs annually. Subscribe here for exclusive dealflow.