Startup due diligence is the process by which an angel investor assesses a company’s prospects of success and reaches a decision on whether or not to invest. It is the discipline that sits underneath everything else in how to angel invest in startups.
That’s easy enough to understand. Implementation is a completely different animal.
I have a few diligence rules that I live by as an investor. The first is that every deal is subject to diligence before investment — zero exceptions. The second is that every deal starts as a no, and you work your way up to a yes through the process.
These guardrails exist because I’ve seen deals that were perfect on paper cross a single red line and die. You’ll never find that line if you don’t look for it in the first place.
The framework I use is continuously combed over across successive deals, but it originated with my decision to invest in Turing.com at seed stage, when the company was at a $15 MN valuation. It was last valued at $2.2 BN at their Series E.
The odds of a seed-stage company reaching unicorn valuation in San Francisco and New York are about 1.5%. Across Y Combinator’s entire portfolio throughout its history, its unicorn rate as of 2026 is 1.8%. If you are investing more frequently than 1 in 100 companies, your selection is too loose. My bar is 300:1.
The honest reality is that there is no coherent definition of what due diligence means, and many investors — from angels to VCs — simply have no idea what they are doing. Comparing my due diligence today to when I started, I’m honestly embarrassed at how I made decisions. The point is that due diligence is a skill set that takes reps to develop.
Many newbie angels I speak to rely on instinct rather than a clear process. The Angel Capital Association’s research into angel group returns found that angels doing minimal diligence returned roughly 1.1x their capital, while those doing substantial diligence returned several multiples of that. The exact multiple is contested, but the message is clear: process beats instinct.
Since venture is a 10-year investment horizon, instinct always plays a role in your decision-making — but it should always be the fallback when objective data is not available, not the starting point.
In this article I’m going to share my eight-point decision framework for what I look at before deciding whether or not to invest in a startup. It covers the product or service, market, economics, defensibility, traction, team, the raise and the exit.
TL;DR — Startup Due Diligence in 60 Seconds
- What it is: a structured pre-investment process in which a company is evaluated across eight areas in order to reach an investment decision
- How long it takes: 1–3 weeks for pre-seed to seed-stage companies, and 1–3 months for Series A and later. Be mindful that funding deadlines are often arbitrary. I encourage investors to take as much time as they need, and not to be afraid to walk away.
- What matters most: conventional wisdom says the founding team matters most. I disagree. My mental model is that the company needs to pass every single area, and cannot cross any red lines such as ethical red flags.
- What you are looking for: investors should look broadly across all dimensions first, then select where to deep-dive. Avoid the instinct to go narrow and deep in the areas that are familiar and comfortable. That leaves a lot of blind spots.
- The bottom line: a thorough due diligence process doesn’t guarantee a win, but it can help you avoid 95% of failures. Building your deal pipeline gives you repetition and mitigates adverse selection, because you are simply seeing more.
What Is Due Diligence in Startup Investing?
Due diligence is an investor’s own process for deciding whether a startup is investment-worthy before wiring the money.
It is about challenging your core assumptions and hypotheses with data where available, and building a holistic view that gives you the confidence to say yes.
At the risk of sounding negative, my best advice for investors is that every deal starts with a no, and you work your way up to a yes during the diligence process.
At the earliest stages — angel, friends and family, and pre-seed — tangible data points simply don’t exist. The company might be pre-revenue. Up to Series A it is not uncommon for startup financials to be unaudited. This is where intangibles like founder quality matter more, and where valuation needs to be commensurate with the higher risk profile.
Why it matters
- Founder pitches and their decks bake in positive bias
- Short of faked numbers, traction doesn’t lie
- Due diligence takes a lot of work, and most angels lazily accept founder numbers at face value. They overvalue signals like other investors and advisors, and their limited deal access means high adverse selection.
Startup investing will always be risky; there is no getting around it. Diligence helps you identify the flags to walk away from. If in doubt, don’t be afraid to walk away.
The number one thing that angels get wrong is executing diligence on the founder’s terms. They assume there is a fixed timeline. Investing in a startup is ultimately a negotiation, and in any negotiation your bargaining position matters. Deal timing is just another leverage point. Why would you be the first $10k check into a $2 MN raise? If the fundraising process might take 4 months, it serves you to see how the company performs over the next quarter, and to see that the round is fully capitalized, before you commit.
How Long Should Startup Due Diligence Take?
Diligence time frames get longer as startups move into later stages.
| Stage | Timeline |
|---|---|
| Angel and pre-seed | 1–2 weeks |
| Seed | 1–3 weeks |
| Series A and later | 1–3 months |
The Angel Capital Association suggests a well-structured process can be completed in under 40 hours — realistic once the work is split across co-investors rather than carried alone.
Competitive deals can move fast when allocation is limited. This underscores my point that startup investing is a negotiation. However, competition for allocation does not necessarily equate to deal quality. In fact, the opposite may be true: when there is an abundance of capital fighting for limited allocation, investors tend to forsake all diligence entirely just to be able to invest.
Deal timing is therefore related to the capital environment. After the funding winter in 2022, I was able to do much more sensible deals, with a normal due diligence process, at reasonable valuations. For example, in Q1 2026 I invested in a water technology company that had grown from zero to a $24 MN revenue run rate in 18 months. The deal was valued on a post-money SAFE with a $75 MN cap. Because this was a company outside the hot AI sector, we were effectively able to invest at 3x revenue in the fastest-growing startup I have ever encountered.
Where it is a legitimately fast-moving deal, your choices are to walk away, undertake limited diligence, or write a blind check and accept the risks.
Due diligence in the real world faces many constraints. You are limited by your expertise, the time you have, your interactions with the founders, and how much information is shared. Learning to prioritize and focus in order to be strategic is a key survival skill.
A 300:1 selection rate, and 4–5 companies a year. That’s my bar for pulling the trigger. It’s possible because of the mechanisms we’ve built to scale our sourcing and diligence capacity. The idea is to be dealflow-unconstrained and to have the ability to make good decisions at scale; that’s not a bug, it’s a feature. Every single company I look at is being compared to every other deal in our pipeline. It is not about a company passing a diligence bar — every company we back is beating out all the other startups in our pipeline.
What Should Be in a Startup Due Diligence Checklist?
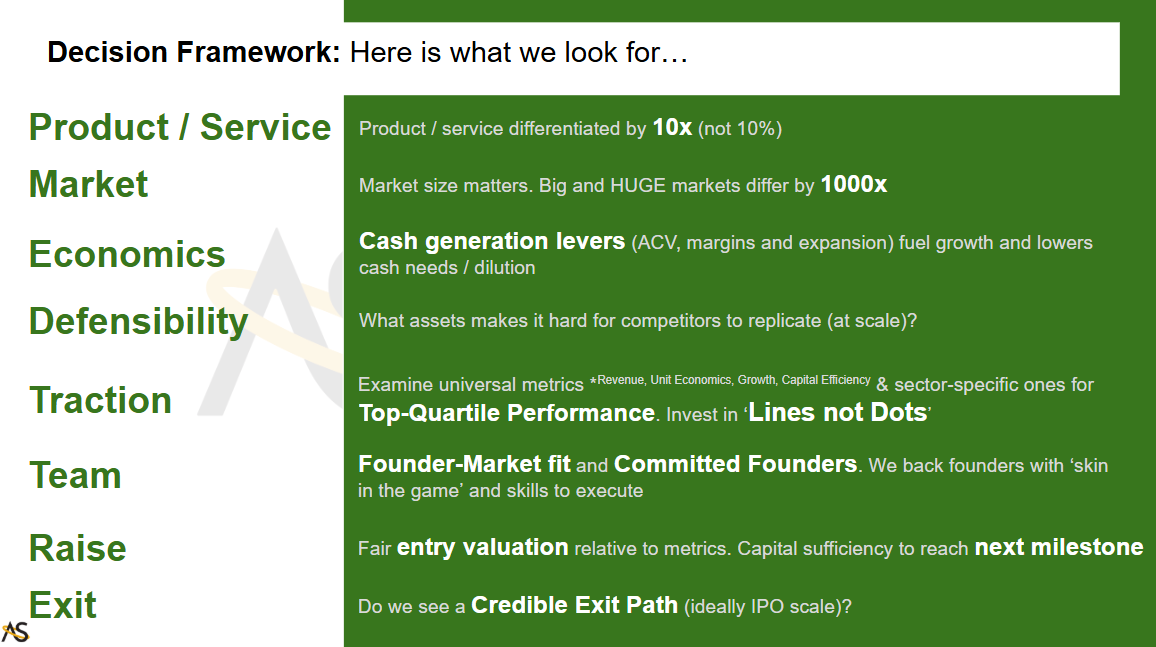
Our due diligence checklist covers eight categories, in no particular order: the product or service, market, economics, defensibility, traction, team, the raise and the exit.
I have never skipped the diligence process. The best founders I’ve backed have all gone through it; it speaks to their fiduciary responsibility toward investor capital. The interactions during the diligence process also help inform a view of the founders.
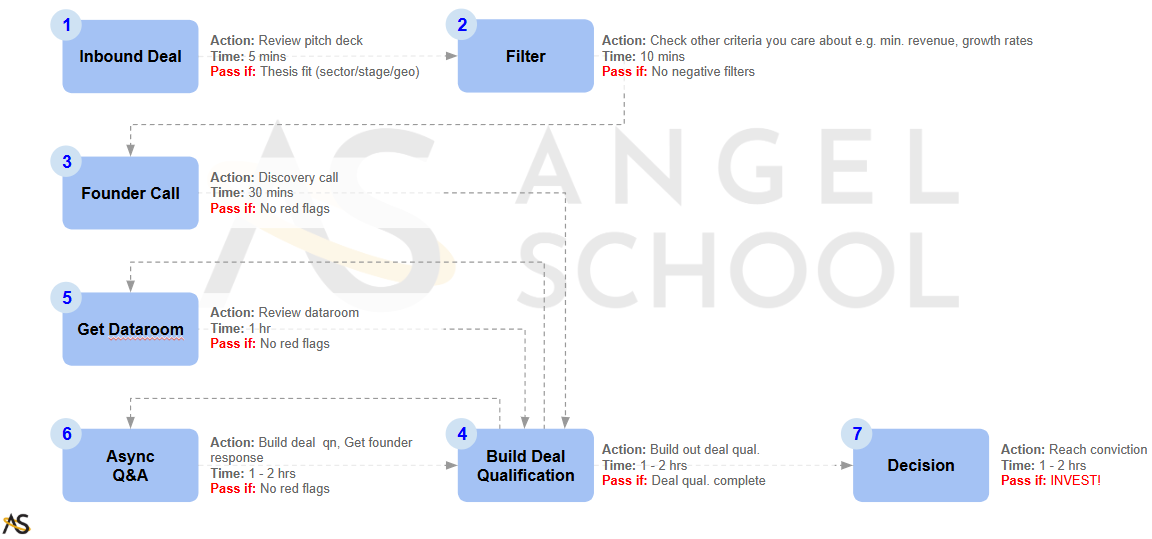
I run a staged process, investing progressively more time as we get deeper in. I’ll spend 2–5 minutes on an outreach message or a pitch deck review, 30 minutes on a first founder call, 1 hour on a data room review, then jump into proper diligence. At any point in this process a deal might be dropped for any number of reasons.
As harsh as it sounds, I am looking for every reason to say no and to move on to the next company. It might be as simple as a company being outside my thesis, a founder side-hustling their startup, performance metrics that aren’t obviously above average, or a broken cap table.
Failing fast is important because it lets you move on to the next deal. The other reason is that the deeper you go into the diligence process, the more your time and effort scale exponentially. That is why 95% of companies never make it to full-fledged diligence.
Here is a diagram of our iterative due diligence process, from first touchpoint to investment decision.
1. The Product or Service
What to check
- The product is commercial and revenue-generating, rather than an MVP, a prototype, or vaporware in a slide deck
- It solves a real market need; in other words, it is a cure rather than a painkiller
- Direct competitors are identified by the startup. Investors are encouraged to do their own research as well — think laterally into adjacent spaces, and ask which players in the value chain could enter this market.
- Its value proposition is 10x relative to competitors, whether incumbents or startups — not 10%
- The product was built and shipped by the core team, rather than by outsourced developers
Questions to ask
- What is your product differentiation against your top three competitors?
- Do your customers have to carve out net new budget, or are you displacing existing tools? If so, which ones?
- What is on your product roadmap for the next 6–12 months?
Red flag: any version of “we have no competition” is either a delusional answer on the part of the founders, or a sign that the market doesn’t exist.
There is a skill to executing founder calls. In 30 minutes you have to meet each other and establish rapport — it is a two-way relationship, in which a founder chooses who to accept capital from as much as an investor decides to invest. I advise investors to prepare for the call by reviewing the deck and thinking through the business. Your barometer for establishing competency and credibility is simply to ask a non-trivial question. That single act distinguishes you as an investor from the dozens or hundreds of other calls in which the founder has to robotically go over their pitch deck.
2. The Market
Market size matters. The difference between a billion-dollar market and a trillion-dollar market is 1,000x. The delta between an above-average founder and an excellent one might be 10x, 20x or 30x. Market size scales much more than team performance.
That said, market size is moot if you don’t have a way to get your product or service out to customers. We bucket go-to-market under market diligence.
What to check
- Total addressable market is large enough to support a venture-scale outcome
- Serviceable obtainable market is realistic for a 3–5 year horizon
- Market sizing is triangulated from bottom-up, top-down and other measures
- The market is growing, not flat or contracting
- The customer ICP is well defined — “everyone” is not a segment
- Regulatory, licensing and growth barriers are understood
- Go-to-market for early-stage companies falls into founder-led sales, product-led growth, or internal sales teams. Partners and distributors are a secondary channel.
- Ask for a concrete go-to-market document, and for channel performance metrics where available
One of my favorite readings in all of venture is an article called “Where to Go After Product-Market Fit”. It is an interview between Elad Gil — a solo GP — and legendary software investor Marc Andreessen of a16z. Marc makes the argument that, particularly in software, go-to-market distribution coupled with a business model with strong unit economics drives cash, which can be used to stay ahead of competition. It is extremely difficult to win on a product level in software, where code is fungible and replicable. In a world of AI and LLMs, where code is cheaper and ubiquitous, this holds true more than ever.
3. Economics
What we care about here is how the business makes money, and the profitability of each sale. The product or service characteristics can lend themselves to organic expansion over time.
What to check
- A clearly articulated revenue model that is in line with how the industry sells, and that generates clear customer value
- Gross margins appropriate to the business model. SaaS companies benchmark to 60–70% gross margins on recurring revenue, whereas consumer products might edge into 70–80% but earn one-off revenue and incur ongoing performance marketing spend.
- Expansion potential from product-led growth, selling more seats, or expanded usage, depending on the business model
Price points and unit economics can change over time, but there is no getting around a chosen business model and the underlying product characteristics that drive expansion and retention. For any startup I encounter, it is fairly easy with a bit of experience to guess the business model and its implications. Asset management businesses, for example, can scale GMV to big numbers but are constrained by tiny unit economics. To put that in perspective, an alternative-assets AI wealth advisor might control $100 MN of AUM. Fees of 2% a year are only a $2 MN revenue run rate, with limited expansion potential, since users are constrained by their financial assets.
I expect any startup I encounter to have a business model — even pre-revenue ones. It is simply inexcusable for them not to have a view on revenue generation.
Investors care about unit economics because high price points with rich profit margins generate cash to fuel growth, rather than raise equity financing, which distracts founders and dilutes investors.
4. Defensibility
Looking for defensibility or moats at the earliest stages is overrated. That said, my framing question is: “What about this business is hard for competitors to replicate at scale?” Scale matters, because true defensibility rarely exists early on. Investors like to hear that a company has patents, but plenty of patents sit around never generating any value, so who cares? Data moats and network effects are a function of scale, so by definition they simply don’t exist at the earliest stages. Regardless, diligence is a process, so be sure to catalog what the company has that could become a source of defensibility.
What to check
- Intellectual property and trade secrets
- Patents
- Go-to-market distribution: a startup’s ability to generate cash can be a moat in itself
- Proprietary data and network effects, which are a function of operating scale
- Scarce, irreplaceable resources, such as founder expert knowledge and access to highly specialized talent
5. Traction
There is a saying that you should invest in lines, not dots. This is where traction matters. No matter how smooth a founder’s pitch, or how polished their deck, you can’t hide from the numbers.
What to check
- Revenue: scrutinize the right revenue metric given the business model. It could be ARR, or annualized revenue for non-recurring businesses. For marketplaces and payment processing, distinguish between GMV and take rate.
- Growth rate: look for consistent monthly growth, benchmarked against top-quartile performance
- Churn: below-average churn rates. High churn destroys compounding.
- Expansion revenue: measurable using cohort analysis
- CAC:LTV ratios: customer value relative to acquisition cost
- Burn multiple: how much cash a company burns in one period to acquire net new revenue in the next
- Customer concentration: as a general rule, any single customer accounting for more than 20% of revenue is high concentration
- Pilots and design partners: paid pilots are obviously a stronger signal than free ones
- Pipeline: lowest on the stack are LOIs and waitlists. They are often hard to validate as indicators of real demand.
Red flags: I have a severe allergic reaction to misrepresentations of revenue — for example, when GMV or grant funding is counted as revenue. This is more common than you think.
Another flag is founders who think funding is a prerequisite for generating revenue. It commonly speaks to a founder’s inability to sell.
When assessing startup metrics, it is critical to understand the benchmarks. Get educated so you know what good looks like. For example, top-quartile companies before Series B should be growing at least 3x year over year. Anything less is fairly uninteresting. Venture is a business of outliers, after all.
6. Team
It is generally true that the founders and the team are the most important piece of the puzzle, and that is especially relevant at the earlier stages. However, it is easy to say, and it is incredibly subjective and hard to measure. I am generally skeptical of any methodology that purports to predict success based on background or pedigree.
What to check
- Founder-market fit: the founder has credible insight into this specific problem, ideally from having lived it. It is otherwise extremely difficult to have an advantage without deep domain knowledge.
- Commitment: we look for evidence of founder commitment. This can come in the form of sweat equity and risk-taking.
- Repeat founders: there is a premium associated with repeat founders. Whether or not their last startup was successful, they have probably learned a lot. It is also a sign of commitment.
- Familial relationships: certain relationships are a concern. I have backed teams built by siblings, but not by spouses. The risk of a marriage imploding in a stressful startup environment is too great.
As investors we are in the business of generating returns, not funding founders. You are well within your rights to say no, and to determine your own red lines. For example, I would never invest in a company where founders are side-hustling or are raising capital without having built and shipped product.
7. The Raise
Angel investors have close to zero control over a startup’s exit path, but are 100% in control of which companies to back. Any hope of getting an exit starts with your entry.
Individual angels writing small checks are price takers. Their unfamiliarity with startup metrics and valuation multiples are key reasons for overpaying.
What to check
- Fair valuation: it is clear that individual angels frequently overpay for startups. My baseline for a SaaS company is 7–10x revenue, calibrated for performance, founder quality and other factors.
- Next milestone: clarify the milestones for the next funding round. Assess whether the company can get there with the capital it is raising, and the downside risk if it misses operating targets.
I led a syndicate investment in WearLinq’s Series A at the end of 2025. This was a company I had been tracking for 2–3 years, and I only pulled the trigger after they received FDA approval for their medical device and started to generate revenue.
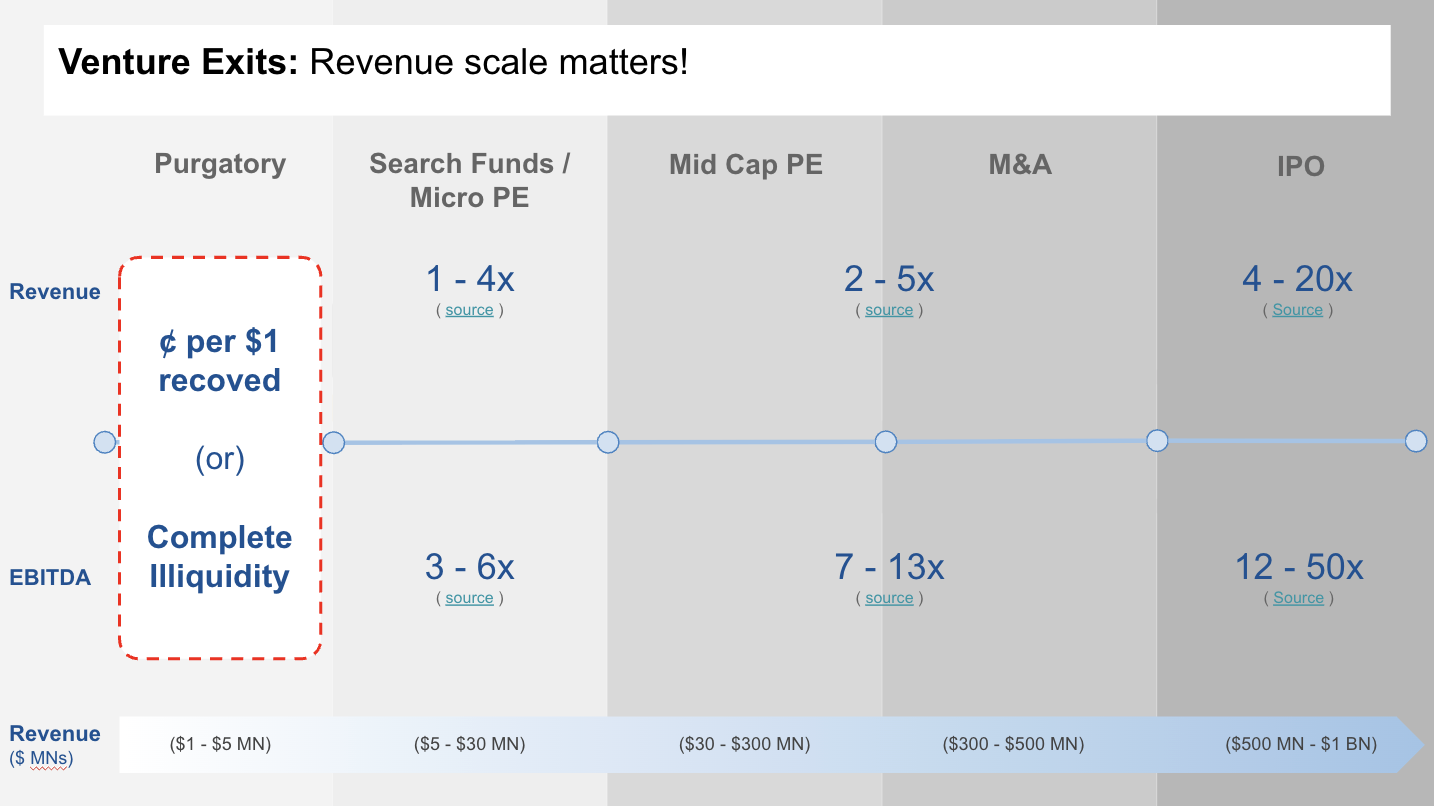
We invested at 7–10x forward-looking revenue multiples, in line with sector M&A and IPOs. It is a lot easier to make a return on a deal like that than to buy in at 30x or 50x revenue and bank on aggressive future growth.
The graph below illustrates revenue and EBITDA multiples at different revenue scales. The takeaway is that being venture-scale matters, because it opens up more exit paths at richer valuations.
8. Exit
You should enter any deal with a clear exit thesis, backed up by market data points such as market sizing and sector exits — ideally IPOs and M&A.
What to check
- Founder response: always ask founders how they plan to get an exit for investors. This establishes an expectation for liquidity, and gives you a sense of the founder’s ambition.
- Assess the response: you need to determine how serious the founder is, and whether they can take the company all the way
We have experimented with weighted scoring on our diligence framework, and ultimately concluded that this level of numerical specificity gives a false sense of precision.
Using AI in this process did not generate better results, since the data set injects varying degrees of positive bias from the founders. Additionally, a non-deterministic output from an LLM results in too much scoring variability.
My recommendation is simply KISS — keep it simple. Think of the diligence framework as a checklist to go through the same way a pilot goes through one before taking off from the runway. Every single line item has to pass, and there can be no red lines crossed. Your instincts as an investor play a big role in decision-making; don’t let that get lost in a calculation that is mathematically correct but loses the art and skill of being an investor.
Red Flags That Immediately Kill a Deal
These are the hard lines that make you walk away from a deal immediately.
| Red flag | Why it matters |
|---|---|
| No diligence shared | Founders out fundraising with nothing but a pitch deck show a cavalier attitude to investor capital |
| Material misrepresentations | Inflated or fabricated traction is an ethical breach |
| Underwhelming metrics | Performance metrics that do not resemble top-quartile performance |
| Broken cap table | A broken cap table shows a history of missed operating targets and overvalued prior rounds, and it hurts the company’s ability to raise future capital |
| Bad founder “vibes” | Investing in a startup is a 10-year relationship. If you don’t get along before the investment, you don’t want to be stuck long term |
| “Wannabe” founders | Building a company is hard. A venture startup is a whole other level. Founders who are not all in on this shouldn’t raise capital |
Three of the most common and fastest red flags to detect — and to drop a deal over — are a broken cap table, a convoluted fundraising history, and underperforming metrics.
One deal I worked on was a European startup that had spent over 8 years developing a deterministic AI for programming CNC machines. Their technology was far superior to competitors’, they were backed by strategic corporate investors, and their growth metrics were trending in the right direction.
In the end we walked away because the company had raised $60 MN to get to $10 MN of ARR over 7 years. Multiple rounds of fundraising meant valuations had been pushed up, and this was a down round.
No matter how professional and expert the founders were, we couldn’t get over the fact that they only owned about 12% of the equity at Series B. If I had started diligence simply by looking at the cap table, that would have been sufficient to kill it early.
Collaborative Due Diligence: Why Angels Should Not Work Alone
Due diligence is a bottomless pit; there is always another rabbit hole to go down. Most of us are knowledgeable or expert in specific areas, which leaves us unqualified to assess other areas of a company in a sophisticated way. That can be improved with a lot of practice, of course, but it only goes so far.
The obvious solution is to turn due diligence into a team sport. Build your networks with other investors early and often, and surround yourself with investors who share a similar thesis but hold different domain expertise. The investing world is very small and interconnected. Investor networks are great mechanisms for sourcing deal flow and for conducting diligence.
There are specialist firms and service providers you can use, but they are usually out of reach for most angels, syndicates and smaller VCs. I am also reluctant to believe that diligence should be outsourced, except for very specific specialist skill sets.
How the work gets shared
- Angel groups and syndicates: investors can band together to split diligence work and assign responsibilities by expertise. Use your network to call on help from others — on a biotech deal, a trained scientist can review the technology.
- Specialist advisors: they might cost a few thousand dollars to engage, and most angels and syndicates won’t have the budget. The broader danger is relying on third parties instead of developing that skill set yourself.
- Co-investors: ask to be introduced to a VC or another significant investor in the round. It is an easy way to build your network and to gather an additional due diligence data point.
Syndicates are by definition an informal consortium of investors. At scale, and with a qualified network, you can very easily level up the quality of your diligence beyond what you could do by yourself. Their accumulated experience and reps feed into the analysis.
Find out how we built a global investor network of 1,500+ LPs, growing organically with zero marketing spend.
The way the AngelSchool.vc investment committee works is that any investor who completes one of our programs is entitled to a seat, no questions asked. Everyone around the table is trained to think like an investor, while bringing their own networks and expertise for us to tap into.
We look at every single deal singularly, based on its potential to generate a return for us and our LPs. We maximize our odds by sourcing more broadly than anybody else, and we have the ability to do diligence more deeply as well.
I don’t know what the next deal I do will be. It is therefore impossible to build a team ahead of time around an unknown quantity. What I can do is build a diverse and engaged expert network that is trained to think like high-functioning venture investors. This is why a strong community matters.
The diligence process is itself a data point. How a founder handles pressure, ambiguity and hard questions over 4 weeks tells you how they will handle them for the next 8 years.
Thinking about launching your own angel syndicate? Our free masterclass covers how syndicates are structured, sourced and run. Register for the Angel Syndicate Masterclass →
How Do You Decide After Due Diligence?
We have given you a framework that we recommend treating as a checklist, and advised against weighted, quantified scoring, because it adds a false sense of precision and does nothing to remove bias.
So how do you make a decision after running through your framework?
I produce a written investment memo that synthesizes all of the essential information in 3–5 pages. Share that document with a core group of investors you know and trust. In our case, I’ll allocate time at my investment committee meeting: everyone gets 10 minutes to read, without the deal sponsor pitching. The IC then asks questions and picks apart the investment case.
After that we call a vote, which requires a two-thirds yes vote in order to pass and be shared with our LPs.
The vote is a simple Google poll in which every investor scores the eight dimensions from 1 to 5, culminating in a decision: “Would you personally invest in this company based on what you have read?” It is non-binding, but the phrasing is deliberate, because we want every IC member to look at the deal the same way as an investor who is risking capital.
The Investment Memo
I am giving away my investment memo template here for you to download and use. If you are interested, I will even share actual investment memos on companies I have backed, so that you can see the clarity of our thinking.
Download the AngelSchool investment memo template →. It is the latest version, and you are free to use it.
Before you go, here is my gift to you: the updated version of our Angel Investing Masterclass. We cover due diligence, venture liquidity and exits, valuations, and first principles on venture investing. Register for the Angel Investing Masterclass →
Frequently Asked Questions
What is due diligence in a startup investment?
Startup due diligence is the process by which an investor evaluates a company before committing capital. It builds a structure that helps the investor assess upside potential as well as downside risk. The framework commonly covers areas such as the product, market size and team. Having a structure guides the process, especially when many angels lean heavily on instinct and do not approach diligence with any rigor.
What should be included in a startup due diligence checklist?
There is no standard definition or industry-agreed framework for a due diligence checklist. That said, they almost universally look at market, competition, traction and founders. AngelSchool’s decision framework leverages eight areas and combines both qualitative and quantitative data points into a single structure.
How long does startup due diligence take for an angel investor?
Due diligence on pre-seed to seed-stage companies can be completed within 1–3 weeks. Series A and later companies increase dramatically in complexity and can take 1–3 months or more. While due diligence does take time, it is important to recognize that investors often have more time to make a decision than founders communicate. Don’t tie your decision time frame strictly to the founder’s stated window.
What is the most important factor in startup due diligence?
A startup has to at least pass every one of the eight areas we look at, and any single red line crossed kills the deal. It is generally true that the importance of founders is higher at earlier company stages, since concrete data points are lacking. However, we caution against the conventional wisdom that teams should be weighted much more heavily.
What are the most common red flags during startup due diligence?
The most common red lines during diligence are a broken cap table, underperforming metrics and a convoluted fundraising history. A founder who is unwilling to undertake basic diligence, and who expects investment on the strength of a pitch deck, is a deal-breaker; they will often rationalize this by saying they are optimizing for speed. In competitive deals angels might not get the chance to do diligence at all — you have to decide for yourself whether that is a line you are willing to cross.
What documents should I request during due diligence?
Every startup that is fundraising should have a data room ready. It can be as simple as a Google Drive folder with a few basic documents: the pitch deck, a financial model with historical numbers and forecasts, a fully diluted cap table, customer contracts and pipeline where applicable, fundraising history documents, company incorporation papers, and standard agreements such as IP assignment.
Can you do due diligence alone as an angel investor?
Yes, and with a little practice you will get a lot more efficient at it. Learn to zero in on the key documents and to identify red flags early, so you don’t waste your time. It is helpful to build a network of other investors to team up on diligence, or to be part of a syndicate or angel network working on deals with a community. Third-party diligence is an option, though usually unaffordable for angels.
How is angel due diligence different from venture capital due diligence?
The distinction between angel and VC due diligence really boils down to the stage of the company and the resources available. Angels tend to invest at pre-seed or earlier, whereas VCs invest at seed stage and later. The due diligence process for angels tends to be faster, simply because there is much less information to process. Angels are also less well resourced than an institutional firm, so the diligence they conduct has to be much more targeted and lightweight.
What happens after due diligence is complete?
After completing diligence you need a decision mechanism. We recommend a written investment memo, and soliciting the opinion of other investors you know and trust. While terms negotiation is sometimes recommended, it is generally unrealistic — angel investors writing small checks are price takers with no leverage to negotiate terms. There are only three decisions available: yes, no, or stay in touch for the next round. Save every investment memo as a codified artifact, so you can review them in future and see your own progression.
Sources
- Angel Capital Association — Returns to Angel Investors in Groups
- Angel Capital Association — Stones Unturned: An Investor’s Guide to Due Diligence in Early Stage Companies
About AngelSchool.vc

AngelSchool.vc is the ultimate Accelerator for Angel Investors - from 1st check to leading syndicates as ‘Super Angels’. We give venture investors world-class training, a global community AND build their track record as a member of our Investment Committee (IC).
The AngelSchool.vc Syndicate is backed by 1500+ LPs and deploys $MNs annually. Subscribe here for exclusive dealflow.